Business
I’m a Dad Who Grew My Company From $0 to $20 Million in Year 1. Now the Product’s Keeping Millions of Babies Safe.
Reading in data-saving mode. Read full article from Entrepreneur website.
Published 10/9/2026 12:29:05 PM
Dad's Baby-Focused Company Grew to $20 Million in Year 1: Owlet
Key Takeaways
- Workman and his co-founders launched wearable baby monitor Owlet in 2015.
- In 2021, the company went public — then received an FDA warning letter.
- Owlet got FDA clearance, focused on lean profitability and has monitored over 2.5 million infants.
This as-told-to story is based on a conversation with Kurt Workman, co-founder and CEO of Owlet, the only over-the-counter, FDA-cleared wearable baby monitor. Workman and his co-founders Zach Bomsta, Jordan Monroe and Jacob Colvin met in college and launched Owlet in 2015, building it from $0 to $20 million in revenue in its first year. The company went public in 2021.
Owlet has served more than 2.5 million babies, monitored more than 21 trillion heartbeats and collected two billion hours of sleep data, per the company. Additionally, Owlet just launched its new Baby Safety Task Force, a committee created to raise baby safety standards across the category, in partnership with legislators, clinicians and other brands.This piece has been edited for length and clarity.
I’m a dad of three. My oldest is 12, almost 13, and my youngest is seven. So this product really came from a dad’s perspective, not from an engineer’s or clinician’s. I studied chemical engineering, but it was the wrong kind of engineering for what I ended up doing with the rest of my life.
When my wife was a baby, she had an undiagnosed congenital heart defect. They sent her home from the hospital, and she had a coarctation of the aorta and then a bunch of holes in her heart. Ten days later, her mom just happened to check on her when she was going into cardiac arrest, and they rushed her to the hospital. Luckily, they were able to do heart surgery that saved her life.
So when we were thinking about having kids, we visited my wife’s cardiologist to see if it was okay for her to get pregnant because she’s had three heart surgeries and will likely have more. They said she would be okay, but our kids were at risk of the same thing. I’m the worrier in the relationship, and I couldn’t let it go. How would I know? What exists for parents at home to monitor the health of their baby? At the time, you had a video monitor and a thermometer. That was the tool set for new parents. Neither of those could help.
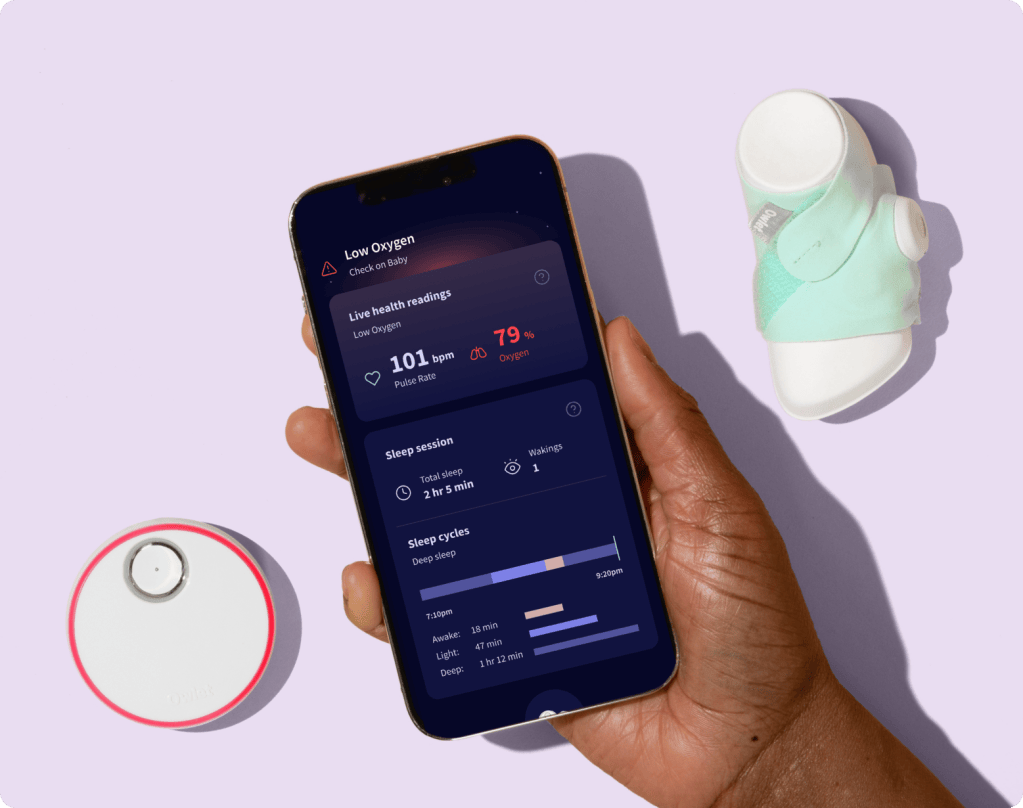
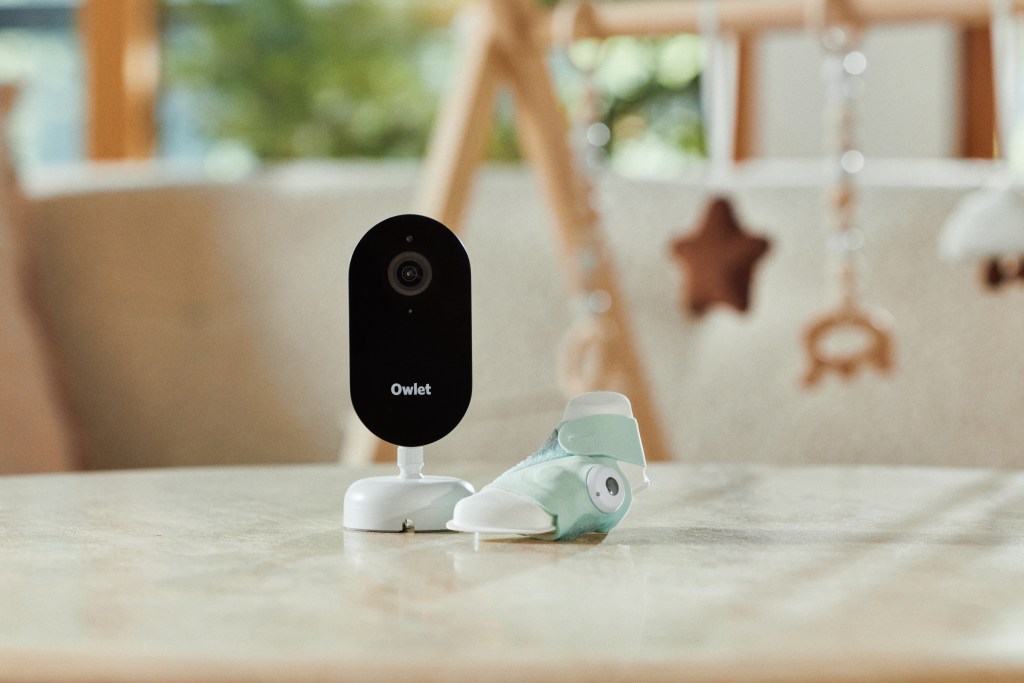
Then I learned about this technology that they used in the hospital called pulse oximetry, which is now in every Apple Watch and Fitbit. It’s an incredible tool that, through light, tracks the pulse rate and the oxygen levels in the blood. In the hospital, with babies, most of the time they put pulse oximeters on the foot. So we came up with this idea of a little sock.
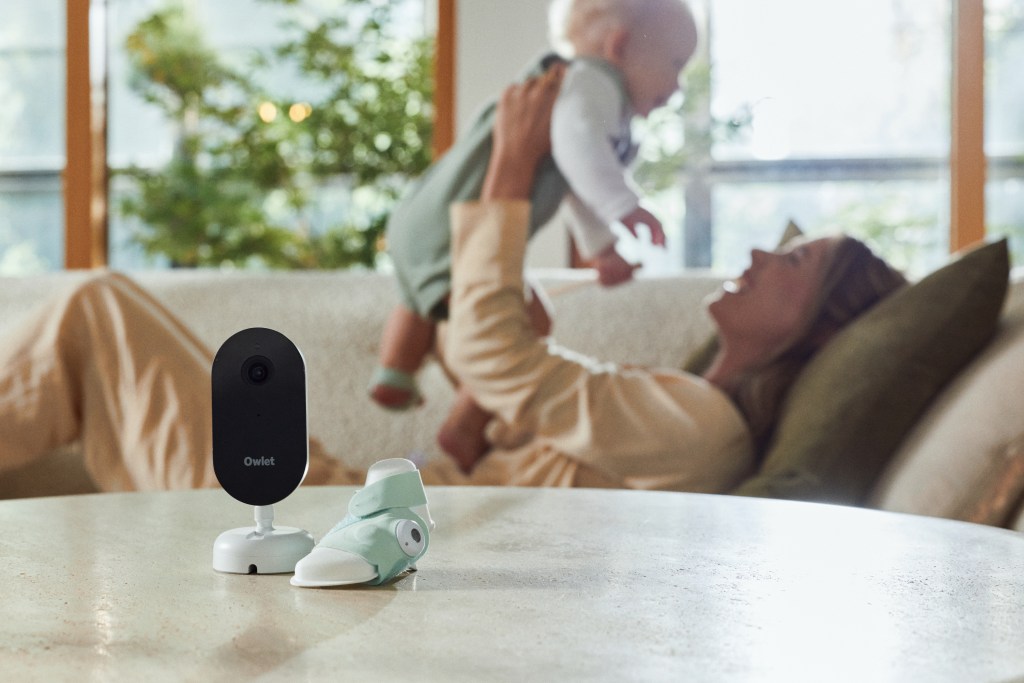
When we showed it to a few parents, their eyes lit up. I remember going to a home where the mom had one of these big, clunky hospital monitors that does the same thing, and she just started crying. I was totally taken aback because I hadn’t actually used one of these hospital monitors before. I’m like, What’s going on? Did we offend her? And she was just like, “It’s awful trying to move this thing around. There’s alarms going off all day. I can’t sleep. I would give anything for that.”
We spent three years developing the product. We did six different beta tests. The first one failed miserably. It just kept getting a little bit better.
It was hard to raise money at first because my co-founders and I had very little experience in that area. On top of that, there was a startup out of MIT that was developing a onesie babies could wear with a sensor that would sense the motion of the belly while they were breathing, and it had already raised money. Then there was another similar company out of San Francisco. Everybody kind of looked at us like, Why would we invest in you?
Crowdfunding, then meeting investors through Techstars
We launched a crowdfunding campaign, and from the dollars in pre-sales, it was okay. We didn’t have a lot of views on our video. There just wasn’t a lot of awareness. But our conversion rate was much higher than some of our competitors because we were focused on this core element — the heart rate and oxygen — and notifying parents if something changed.
That focus allowed Owlet to gain some traction. Then we went through the Techstars program in New York. That got us outside of Salt Lake City into a broader network. We met our first investors. One was a woman named Milena Adamian. She’s a cardiologist out of New York City. She had a medical device-focused fund called Azimuth Ventures. Then the other one is John Frankel with ff Ventures out of New York City. He had a strong thesis around IoT and connected hardware. So it was a perfect blend.
When we launched in 2015, we thought that the best strategy would be to buy ads when somebody searched for “baby monitor” on Google. Because millions of parents search for a baby monitor. That failed miserably because they already knew that they wanted a video monitor and audio monitor. So our bounce rate was terrible; our conversion rate was awful.
Pivoting to educate parents on Owlet’s new category
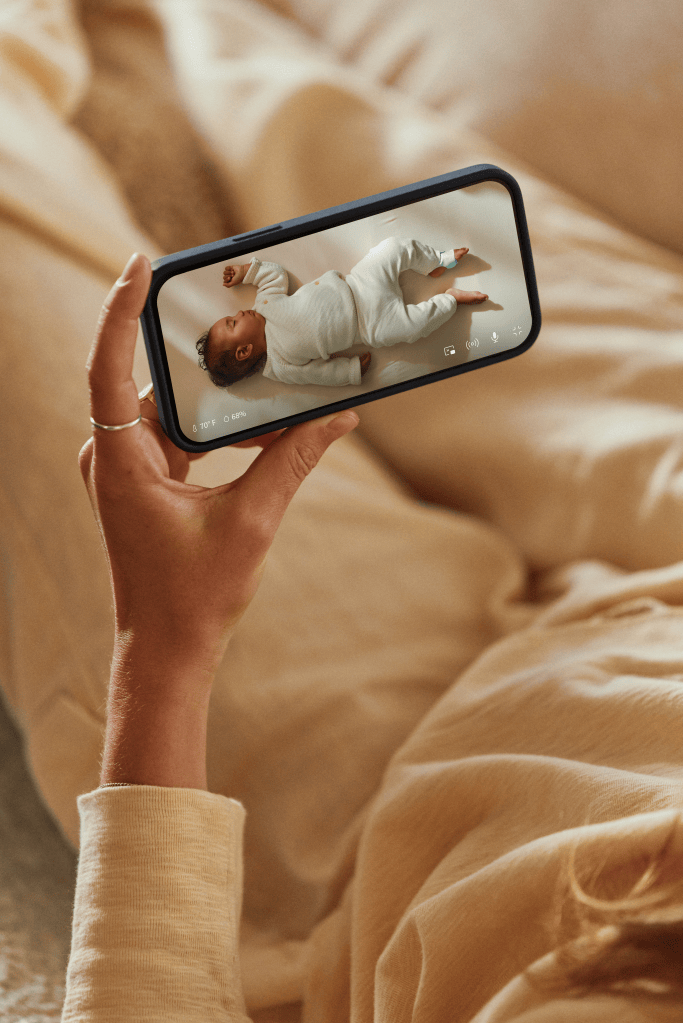
We pivoted pretty quickly and realized it was all about education. This was a new category. We couldn’t assume that biometric monitoring for babies was obvious — because it wasn’t. We switched the strategy to heavily focus on PR, influencer partnerships, video content to educate, and that started to get some traction.
Also, we avoided retail the first year. We had interest from Target, Buy Buy Baby and some other retailers. But we wanted to spend all the margin dollars on building awareness and education. We ended up driving 50 million video views that first year. We had a ton of great press. That first year, we went from $0 to $20 million in revenue — with no retail, no partners, no Amazon, just on our website.
That then opened the door to retailers. We got better placement on the shelf. We had better margins, so we could do more marketing to support the retailers. Owlet just started to explode in retail. This was a new category, so every dollar for retailers was incremental to their baby category.
Going public and receiving an FDA warning letter
Then, in 2021 Owlet went public. That was intense. There were a lot of companies going public through stocks, so there was just a lot of activity happening in the market. We went from going out to raise a round of capital, our Series C, to getting this offer to go public at a great valuation with a lot of money attached to it. The offer was so much better than anything we were looking at raising privately that we decided to go for it. It was an expensive and time-consuming process to go public. Then, right after going public, we got a warning letter from the FDA.
The FDA said that we had not classified the product correctly. Most of these wearables are wellness devices, and we had positioned our product in that way. All of our labeling, all of our claims, the feature set. The FDA disagreed with that, so for one quarter, we had to take the product off the shelf. We were able to negotiate with the FDA to get it back on the market, prior to getting clearance, with a changed feature set. Then we worked on getting FDA clearance over the next year and a half.
Getting FDA clearance and regaining sales momentum
In that period of time, our sales dropped by about 30%, then dropped again, before they started to climb back. We got clearance at the end of 2023 — and saw sales double overnight. It was a huge win for the company. But by that point, not only had the stock market kind of crumbled, and you lose a lot of investors through that, but also this FDA overhang created a lot of overhang for the business, and that was a scary time where we had to get to profitability.
So we built a leaner business. We learned that our biggest expense was marketing. We’d thought that our marketing was efficient and contributing to sales. When we cut marketing by 80% out of necessity — we were spending about $3 million a year — we learned that 85% of the traffic still came to our website, and the other 15% went to our page on Amazon or Target. We were just paying a $3 million tax to Google.
Owlet bridges the gap between hospital and home
Since then, we’ve doubled down on our focus: How do we help bridge the gap between the hospital and the home? Unfortunately, more than 4,000 babies pass away unexpectedly in the home every year. Babies are naturally vulnerable. We’re using healthcare as this giant triage clinic, and our goal was to bring that home. We launched our data subscription platform that built out that data, and this year, we integrated telehealth into our service. So we’re trying to build that ecosystem. We also launched our first hospital partnerships and opened up medical record integrations so that data can flow seamlessly to physicians.
Even though we’ve had ups and downs in our journey, the level of adoption from parents is amazing. Almost one in eight babies in the U.S. now has an Owlet. We think pretty soon that will be one in five. So the adoption of this new category has been incredible. It’s higher than any other from an adoption percentage basis, higher than any other new wearable. So we’re really proud of that. We’re also seeing incredible adoption of our subscription, which means this data is empowering parents. And, again, we’re the first and only FDA-cleared monitor. It’s amazing what we’ve been able to move in this category.
§
Opinions expressed by Entrepreneur contributors are their own.
Key Takeaways
- Use AI to reclaim time for strategic work. Automate routine tasks and build systems that let you focus on the decisions and challenges that require your expertise.
- Build a business that can grow without your constant involvement. Develop your team’s problem-solving skills, invest in lasting relationships and share credit to create a stronger, more independent organization.
Throughout my career as a business leader, entrepreneur and executive coach, I’ve learned to focus on the work that matters most — the decisions, challenges and relationships where my experience and judgment make the biggest difference. That means building better systems, developing new skills, strengthening relationships and empowering my team. These investments compound over time, helping my businesses grow without requiring me to weigh in on every decision.
If you want to do the same, here are five practical changes you can make today.
1. Stop doing everything. Start building your AI stack.
Doing less yourself doesn’t mean working less. Your value isn’t measured by how much you personally execute. Administrative tasks can quickly consume your day without moving your business forward.
I divide my workload into two categories: below-the-line and above-the-line work. Below-the-line tasks include email, scheduling and project tracking. Above-the-line work is where your judgment matters most: setting strategy, making critical decisions, solving problems and building relationships.
AI creates opportunities to move more work below the line. Start by listing what consumes your time, then determine what you can automate, delegate or eliminate. Build a focused ecosystem of AI agents that can research your industry, track competitors, monitor key performance indicators (KPIs) and prepare meeting notes.
This approach helps me protect 90-minute blocks for deep work, giving me more time to focus on challenges that genuinely require my expertise. After spending too many years on below-the-line tasks, my advice is simple: Let AI handle more of the administrative work so you can focus your best skills on what matters most.
2. Stop thinking you know it all. Start updating your skills.
The moment you think you know everything may be the moment a competitor passes you by. Maintaining a humble, curious mindset has helped me recognize new opportunities, grow as a leader and strengthen my businesses. Learning doesn’t end with a degree. Keep developing new skills, pursuing relevant credentials and embracing a learner’s mindset throughout your career.
AI is a good place to start. Go beyond basic chatbot prompts and learn how AI agents, automation and interconnected systems can work together to improve your business. One agent might research competitors, another monitor regulatory changes and a third identify potential investors or financing opportunities. AI can also surface emerging industry topics, creating opportunities to contribute thought leadership before a conversation gains momentum.
I recommend programs from Vanderbilt Executive Education and MIT Professional Education. Both offer focused learning opportunities centered on executive strategy without getting lost in the technical details.
3. Stop taking over every project. Start coaching your team.
Entrepreneurs are often wired to jump in and solve problems immediately. Eventually, that instinct can become counterproductive. You’ve built a team for a reason, and neither you nor your employees need you involved in everything.
I learned this firsthand as an executive at Intel. During a period when I was pushing myself too hard, the pressure spilled over onto my team. Instead of delegating thoughtfully, I sent early-morning emails and created unnecessary work. When team members told me they were stressed, it was a wake-up call. I realized my team needed me to operate at my best and help them do the same.
I started with a simple coaching principle: Stop offering answers and solutions too quickly. When someone brings you a problem, ask them to recommend a solution, too.
Try asking questions such as:
- What do you think we should do?
- What are the primary risks?
- What does success look like?
If you want your team to think strategically, give them opportunities to contribute to important decisions. Challenge their thinking, encourage them to evaluate trade-offs and let them own the solutions.
You’ll gain a better understanding of their strengths while developing decisive leaders who can exercise sound judgment without relying on you for every answer.
4. Stop networking. Start building lasting relationships.
Networking in the digital age can mean little more than accepting an invitation or adding a connection. But a connection is only the beginning. Would that person invest in you or your business? Could you call each other for advice, an introduction or a potential partnership?
The strongest relationships become more valuable over time. Alpine Investors founder Graham Weaver calls these “lifetime relationships.”When Weaver started his company at 28, he struggled to raise funds. Two investors with whom he had built relationships eventually backed him, helping get the business off the ground. He has said the company wouldn’t exist without their belief in him.
Building lasting relationships requires more than accepting another LinkedIn request. Someone you meet today could eventually become a strategic partner, join your board or help you raise capital. One day, you may be the person they turn to.
Prioritize meaningful relationships over simply accumulating social media connections. Invest time in being authentic. Send the card. Check in when you don’t need anything. Pick up the phone when someone calls for advice.
These small gestures build trust over time and create a network of people who will be there when it matters most.
5. Stop chasing recognition. Start sharing the spotlight with your team.
At a certain point in your career, success becomes less about what you accomplish personally and more about the leaders you develop.
Sharing credit is also a performance strategy. It recognizes strong contributions, reinforces positive behaviors and builds a team capable of achieving more without routing every decision through you.
Give talented employees opportunities to take ownership. Include them when recognition is given, let them lead presentations, put them in front of clients and trust them to make important decisions.
Research from Gallup found that 61% of employees who received both feedback and recognition from their manager at least weekly were engaged, compared with 38% of employees who received weekly feedback but less frequent recognition.
When your people deliver results, make sure they receive the credit. Recognizing their contributions reinforces a culture in which people feel valued and motivated to do their best work.
Build your own playbook
Think of these five shifts as a starting point, not a rigid formula. Put them into practice, pay attention to what works and adjust what doesn’t.
Through experimentation, you’ll develop an approach that fits your leadership style, your business and your team. Keep investing in the systems, skills and relationships that help you operate at your best.
And never stop looking for that edge.