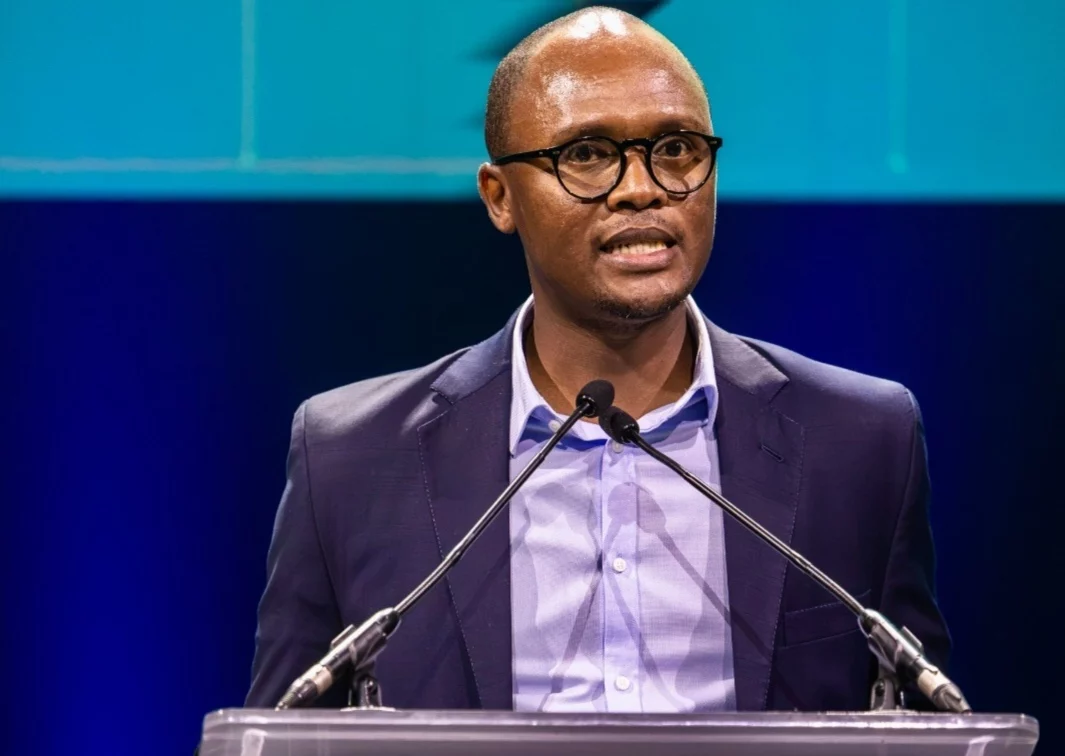
After investing in tech startups across Africa for the past seven years, Enza Capital has launched a dedicated fund just for artificial intelligence (AI) startups and AI-enabled startups in Africa, on the view that African venture capital is maturing and that specialist funds find and support the best companies more effectively.
“AI is the most consequential technology shift in a generation, and it needs to be harnessed to create value for a broad set of people,” Mike Mompi, Enza’s managing partner, said on a call with TechCabal. “That is why investing in AI in Africa now is an incredible opportunity and even a responsibility.”
The firm’s name comes from a Zulu word meaning ‘to build’, ‘to make’ and ‘to create’; it has raised $58 million across its first two funds and says it has made 75 investments across 47 companies in nine African countries.
Mike Mompi started Enza in 2019 with two co-founders. Sir John Lazar ran Metaswitch, a communications software company backed by Sequoia Capital and Francisco Partners, which Microsoft bought in 2020. David Cohen worked at Goldman Sachs in London before spending about two decades as a partner at Farallon Capital, the hedge fund.
By Enza’s count, AI took about 60% of global venture investment in 2025 and just over 5% in Africa. While Enza does not expect African startups to compete with frontier models because the capital required is too large, it is betting on companies that adapt AI to African conditions.
These African adaptations could include voice tools that understand Pidgin and code-switching for customers who cannot read, smaller models trained on local data, and computing that works where connectivity is patchy. The firm calls this the constraint advantage, the idea that products built for Africa’s limits can also work far beyond it.
That thesis shapes what Enza looks for. As building a prototype gets cheaper, the firm says, founders need deep knowledge of their market and a moat that cannot erode: data no one else has, existing routes to customers, or a product built into the daily work of the people who use it.
Enza also screens hard on cost. AI startups pay for every query their product runs, so a business that assumes cheap inference can be wiped out if that cost doubles. The firm backs companies with high margins or a clear path to them and expects open models and cheaper local computing to bring costs down.
In this conversation, Mompi explains why Enza is raising a fund dedicated to AI, why he believes African AI companies will win through local data, distribution and fit into customers’ daily work, what he looks for in founders, how he thinks about the cost of running AI models, and how Enza plans to return money to its investors.
This interview has been edited for length and clarity.
Why a dedicated AI fund for Enza?
African venture capital is following the pattern of other emerging markets. Funds start as generalists and specialise as the market matures. A specialised fund is better at finding the best opportunities and helping companies reach good outcomes, because focus brings networks, relationships and insight into what is happening globally and locally.
We have invested in African technology for nearly a decade, and with our team, our knowledge and our mix of local and global networks, we believe we are one of the firms best placed to run an AI fund for Africa.
Sir John Lazar spent three decades as an engineer, raised money from Sequoia Capital and Francisco Partners, and sold that business to Microsoft. He is president of the Royal Academy of Engineering, which runs the Africa Prize for Engineering Innovation; that is where we spent time together before launching Enza. He also chairs the Raspberry Pi Foundation, which owns the trading business Raspberry Pi, and guided that business through its listing on the London Stock Exchange.
Sir John runs our office of the CTO, alongside two CTOs in residence, which is rare for a venture team on the continent. One was head of engineering at Yassir, the Algerian super app. The other led engineering at Founders Factory Africa. That depth lets us support our companies on technology. We also run a community where CTOs across our portfolio learn from each other and workshops with outside experts on putting AI to work for companies that are AI-first and those that are not.
We brought AI Tinkerers to Africa as an operating partner and sponsor. It is a network of about 1,300 builders working on AI products in Nairobi, Lagos, Cairo and Johannesburg, and we have run sessions with partners including OpenAI and Microsoft. The aim is to give engineers and early founders a place to show their work and meet people they might not otherwise meet.
Since 2025, we have published our thesis on what AI means for Africa through our Substack, African Vector. It is where we share our thinking and invite challenge.
AI is the most consequential technology shift in a generation, and its value needs to reach a broad set of people. Private AI investment has grown fivefold over the last five years, but Africa’s share of that growth has been marginal. AI took around 60% of global venture investment in 2025 and just over 5% in Africa. That gap is an opening, and we believe AI will be one of the biggest long-term sources of value on the continent.
Beyond the size of the opportunity and the funding gap, what draws Enza to AI investing?
AI is collapsing the cost of building things, and it lets African founders sell globally from day one. More specifically, three things.
The first is local context. There is an opportunity in AI systems trained or adapted for African languages, cultures and operating conditions. Building the same thing as Anthropic or OpenAI would take more capital than Africa can raise. The question is which models suit which places and uses, from small language models with millions or billions of parameters to large ones with hundreds of billions or trillions.
Global models often miss local context. We saw it early on with facial recognition built in the US that could not recognise non-white faces, and we see it now with voice AI that struggles with Pidgin and with speakers switching between languages mid-sentence. A bank customer or mobile subscriber who cannot read and can only use voice is shut out. Add background noise and different dialects, and the problem grows. Africans are now building models that handle this, trained on African data and deployed in African companies. We have invested in one, Aethex AI, and others include Lelapa AI, Intron and ToumAI.
The second is proprietary data. Companies need defensibility, so they are not building a feature that sits on a frontier model’s roadmap. They can build unique datasets and feedback loops that make their AI more accurate over time. Hakimu AI, one of our companies, has access to hundreds of thousands of previously unpublished Supreme Court case files, which it uses to train a small language model that helps East African courts deliver faster, more consistent justice.
The third is infrastructure and compute. How do you make AI work where connectivity is limited or patchy? That means running models on devices at the edge, mixing types of hardware, and building systems that cannot assume abundance. Solutions built for those constraints can also work globally.
Five years ago, we invested in Guidewheel, founded out of Stanford, whose first deployments were in Kenyan factories. It collects machine data and processes it in the cloud to help factories run longer and cut energy costs. Its customers report an average of 41% more output from existing equipment, and we have seen energy costs fall by about 15% a month. It has since scaled across North America, raising from Greycroft and from Decarbonisation Partners, a joint venture between BlackRock and Temasek.
Many investors I speak to see AI as a tool for solving local problems faster, with the edge coming from local context. Do you agree?
Yes. We see AI as a means to an end. We are building an AI fund because we believe AI will let a generation of African founders, businesses and possibly governments solve problems that could not be solved before.
AI changes the economics. Smaller teams can build more ambitious companies with less capital, which matters even more in thin capital markets like ours.
We see two types of companies. AI-native companies have AI at their core, and their revenue comes from it. AI-enabled companies, which is almost every technology company raising money today, spend part of their budget on AI tools to work more efficiently.
You say Enza has done the most AI investments in Africa recently. How many deals, over what period?
I believe we are the most active venture fund making AI-native investments in Africa, but I would be happy to learn that others have done more so we can co-invest. The opportunity is far larger than any one firm. We have made 11 AI investments and are working on our 12th.
Quro Medical, a South African health tech company, is one we have exited.
Hakimu AI is the legal tech business I mentioned. When people in New York or San Francisco ask how you can build AI in Africa, it is one of the examples they understand.
Lua was the first African AI business to go through Y Combinator in its Fall 2025 batch. We had backed one of its co-founders in an earlier, non-AI business. Lua builds AI agents for businesses, mostly African companies, though it has customers on five continents.
Aethex AI builds local language models, starting in Francophone and Anglophone West Africa, and is already selling them. It also built Kora, one of the leading benchmarks for local language models.
WideBot, started in Egypt, built the first Arabic language model that handles multiple dialects. It now has 14 governments and more than 400 businesses as customers.
At the infrastructure layer, there are Guidewheel and Satlyt, which announced its seed round in October. Orca Fraud and Buguard are AI-first cybersecurity companies.
What does the ideal startup for this fund look like?
I would describe what we look for, since it does not depend on a specific business or sector.
People still matter most. Founders need deep expertise in the market they are building for. Prototypes are getting easier and easier to build, so a founder who does not know the market ends up alongside everyone else who built something similar. We look for founders who are ambitious and realistic, with ambition that comes from deep knowledge of the market.
Then it depends on where a company sits. We think of the stack in three layers: infrastructure, platform and application. Building gets cheaper as you move up toward applications, so there is more competition, and you need a stronger moat. At the application layer, that moat can be proprietary data, distribution through existing customer relationships, or workflow integration, where the product becomes part of the daily work of the people who buy it.
Moving down the stack, capital costs rise, and competition falls. Look at Cassava and the GPUs it is bringing into Africa. We are building something for the ecosystem with Cassava that we will announce shortly. Few companies can operate at the scale Strive Masiyiwa can, with his expertise and access to global capital. Infrastructure needs economies of scale. Edge compute is one opportunity, and that is where Satlyt sits. As an early-stage software startup, it plugs into existing scale, optimising communication between satellites and GPU capacity, without building that scale itself.
The platform layer, between the two, is the trickiest, because competition comes from every side. There you need a real technology moat that a large language model company will not roll over.
The last thing is the business model. Many AI companies are moving from charging for usage to charging for results. If a bank receives 10,000 calls a day and can handle 1,000, it misses 9,000. A voice agent that handles all of them and resolves customers’ problems could be worth hundreds of thousands, or millions, of dollars to that bank and could be priced as a share of the profit it creates.
How do you think about exits for this fund, and can you tell me about the exit you mentioned?
For an investment ecosystem to work, investors need their capital back plus a return for the risk. Exits at scale have been missing in Africa, but we have enough signs to believe they are coming.
We are seeing more mergers between companies. Industry players are building teams to acquire technology companies. Global companies are looking for growth outside their home markets. Several IPOs are in progress, which is raising awareness and participation.
We are also working on it ourselves. With co-investors, we helped launch Clearflow Markets to make it easier to buy and sell shares in private companies. We cannot wait for liquidity to appear. We need to build routes to it for our companies, our LPs and ourselves.
Quro Medical built wearable technology, using machine learning, so that a patient who would have spent ten days in hospital could spend two there and eight at home. It worked so well that hospitals began asking why patients should only wear it at home. We co-led a round early in Enza’s life, and in 2025 we sold our full stake, alongside other investors, to the largest publicly listed hospital group in South Africa.
Application-layer AI startups pay for model and inference costs, which squeezes margins. What gross margins does Enza want to see early on?
If you build a business assuming a certain cost for your core product and that cost doubles, you can go out of business if you cannot adapt.
One reason an Africa-specific AI fund makes sense is that our companies do not have to rely on global models to solve local problems. Open-source and open-weight models, and initiatives we are part of, are cutting the cost of training, running models and accessing compute. Some work needs GPUs, and some needs CPUs, so knowing where a model should run matters. There are also initiatives such as the Enzi Prize, a $10 million prize for highly capable, open and affordable AI in Africa.
Margins matter. Many businesses got into trouble between 2020 and 2022 by chasing headline numbers such as total transaction value and ignoring margins. Net profit margin and free cash flow matter even more than gross margin. We look for businesses with high margins or a clear path to them. Companies are also innovating with smaller models, local compute and on-device AI, so we expect costs to fall.
There is also huge and probably unreasonable overinvestment in AI infrastructure globally, which risks overcapacity. Not all AI is fundable, and capital put to work without a deep understanding of the technology risks being lost. That is why it matters to understand where value is being built and where it will stay, for each business, each country and the continent.