×
Tech

Cascador and Sterling launch $200 million fund to derisk startup loans

Cascador & Sterling launch $200m fund to back startup loans

Cascador, a Nigeria-focused platform for growth-stage founders, and Sterling Bank, a mid-size Nigerian commercial bank, have set up a $200 million fund to help small Nigerian businesses and startups get bank loans by sharing the risk of borrowers defaulting. 

The partners say the SME Credit Backstop can back up to $1 billion in loans at a time. Rather than directly lending to the businesses, it will guarantee part of the bank’s potential losses if a borrower defaults, making it easier for lenders to extend credit to companies they might otherwise consider risky.

The fund will consider businesses nominated by venture capital firms and studios that already back them. It will use AI-powered underwriting to check whether the business is ready to take on debt. If it approves the business, the fund agrees to cover part of the bank’s loss if that loan goes bad. 

The fund targets a persistent obstacle for most Nigerian startups: access to debt. About one in five Nigerian businesses had a bank loan or line of credit in 2025, compared with 22% across Sub-Saharan Africa and 36% globally, according to World Bank Enterprise Survey data. Banks often consider small businesses and startups as risky and demand collateral that many cannot provide.

“By sharing risk with lenders and translating community trust into a bankable signal to lend, the fund can help more businesses access what they need to scale and create jobs,” said Trish Thomas, Cascador’s CEO, in a statement shared with TechCabal.

Sterling will decide whether to lend after conducting its own checks. The bank will disburse approved loans, collect repayments and pursue borrowers who default. The backstop is intended to reduce the bank’s exposure, not eliminate it.

Obinna Ukachukwu, a group executive at Sterling Bank, said the backstop, combined with borrowers recommended by funds that already know them, gives the bank “greater confidence to provide larger, longer-term loans.”

Borrowers can start with local-currency loans worth up to $250,000, and the fund plans to raise that to $1 million. 

The partners expect to raise the backstop capital from philanthropic funders, impact investors and development finance institutions. The $200 million is therefore the fund’s stated size, while the $1 billion figure represents the lending capacity it aims to support.

“The future cannot be sustainably built on one layer of the capital stack,” said Iyinoluwa Aboyeji, founding partner of Future Africa, in the statement. “Equity must work with debt and long-term securities to provide builders with the capital they need to build the future.”

Without access to loans, startups must rely more heavily on equity financing to expand, giving investors ownership stakes in exchange for capital. But venture funding has become harder to secure. Only 190 African startups raised $100,000 or more in the first half of 2026, the lowest number since at least 2021. Companies unable to borrow either give up more ownership and control at the early stage or grow slowly.

Debt has become a larger part of African startup financing, although it remains concentrated among a relatively small group of companies. Startups on the continent borrowed a record $1.64 billion in 2025, and debt made up 41% of all their funding, up from 17% in 2019. TechCabal Insights tracked another $614 million in startup debt in the first half of 2026, about 43% of all funding. Over five years, 169 African startups announced debt deals, against nearly 1,900 that raised equity.

The new fund is designed to widen access by letting lenders share the risk of lending to businesses with revenue and existing investors willing to vouch for them. The move also builds on an earlier partnership between Cascador and Sterling. In 2025, they partnered on a $2 million catalytic fund that gave Cascador alumni debt at interest rates around 20%, with much lower collateral requirements. At its June 2026 Pitch Day, the fund handed out more than $5 million, including a ₦2.5 billion ($1.7 million) debt facility to Agriarche, an agritech startup.

The new fund expands that model beyond Cascador’s alumni. Under the earlier arrangement, Cascador nominated and guaranteed borrowers while Sterling provided the loans. The SME Credit Backstop Fund will also accept nominations from other venture capital firms and startup studios.

The fund will operate through Riverwell Platform Holding Limited, a UK-owned company, and Riverwell Platform Services Nigeria, a Nigerian operating company. The Nigerian company will handle partner coordination, borrower assessment, data collection, and portfolio monitoring. A separate reserve company will hold the backstop capital. Ukachukwu will serve as a director on the Riverwell platform.

True scale demands moving beyond surface-level integrations to robust execution. We’ve filtered the noise out of Moonshot 2026, optimising the conference strictly for high-calibre connections between startup founders, global financial operators, enterprise leaders and individuals rewiring Africa’s technical frameworks. Get 20% off Early Bird tickets for a limited time.

Moonshot mast head

§

Making cryptocurrency payments easier to use is as much a challenge as building the infrastructure behind them, Breet chief operating officer Vivian Mbene told Moonshot by TechCabal in Lagos on Wednesday.

Mbene said the company’s biggest task was making a complicated product appear simple to customers, allowing businesses to accept digital assets without taking on the operational demands of managing them.

Breet, founded in 2019, converts cryptocurrency into cash for individuals in Nigeria and Ghana. It also offers an application programming interface that allows businesses to accept crypto payments and receive settlement in local currency.

The proposition separates the payment method from the currency a merchant ultimately wants to hold. Customers can pay with digital assets, while businesses receive local money without having to build a crypto operation of their own.

For Mbene, the objective is to reduce the work required to complete that transaction. “We’re just obsessed with simplicity,” she said.

That approach places much of the complexity behind the scenes. Functions such as monitoring transactions, routing deposits and converting currencies need to work together without requiring merchants to manage each step themselves.

But making the process look straightforward can create a different problem: convincing customers and business partners to trust it.

“Sometimes simplicity brings suspicion, and when it’s powered by crypto, the suspicion kind of doubles,” Mbene said.

Her remarks highlighted a tension for crypto payment providers. A simpler interface can reduce the effort involved in using a service, but it does not necessarily remove doubts about the technology underneath it.

Breet’s pitch is that businesses should be able to use crypto as a payment channel while continuing to manage their finances in familiar currencies. For providers pursuing that model, the commercial test is whether they can make accepting digital assets both straightforward and credible to merchants.

§

Luno, the UK-headquartered cryptocurrency firm that operates in four African countries, spent much of its first decade building a retail crypto exchange.

Now, Ayotunde Alabi, chief executive officer and country manager for Luno Nigeria, says the company is pursuing a bigger ambition: selling digital asset infrastructure to banks, asset managers, fintechs, and large enterprises.

Luno wants to give institutions the tools to offer digital assets to their own customers, issue stablecoins, and move money across borders, Alabi told TechCabal in an interview.

“Luno would be the rail [on] which they [institutions] can come into the virtual asset space. For example, asset managers, banks—if a bank wants the ability to mint a stablecoin, they can plug into our rails [to do that],” Alabi said. 

The strategy marks a shift for the 13-year-old digital asset company, whose business has centred on retail customers buying and selling cryptocurrencies over the years. Retail remains part of Luno’s strategy, but institutions are becoming another major customer segment for the infrastructure it has built.

In July, Luno cut its global workforce by 20%, according to Bloomberg. The layoffs affected the company’s South African team and 5% of its employees in Nigeria, Kenya, and Uganda. Following the restructuring, James Lanigan, Luno’s chief executive officer, said the company would continue investing in retail products while expanding its business-to-business (B2B) offering. 

At the centre of the new strategy are three related businesses: Luno itself, stablecoin issuer BlockTower, and payments company GTXN, which Luno acquired in September. Alabi declined to disclose the value of that deal.

Luno remains the exchange where customers can buy and sell cryptocurrencies and stablecoins. BlockTower, which Alabi said operates as a Luno subsidiary, issues stablecoins. GTXN provides the payments infrastructure needed to connect those digital assets to the traditional financial system, including local collections, payouts, foreign exchange (FX), virtual accounts, and settlement.

“We see GTXN less as another exchange and more as part of the financial plumbing required to make cross-border payments work effectively,” Alabi told TechCabal in an interview.

Luno’s institutional offering has three parts. The first is Crypto-as-a-Service, which would allow banks and asset managers to offer digital asset products without building their own trading, custody, and wallet infrastructure. The second is a cross-border settlement network powered by GTXN’s payments capabilities. The third is stablecoin issuance through BlockTower.

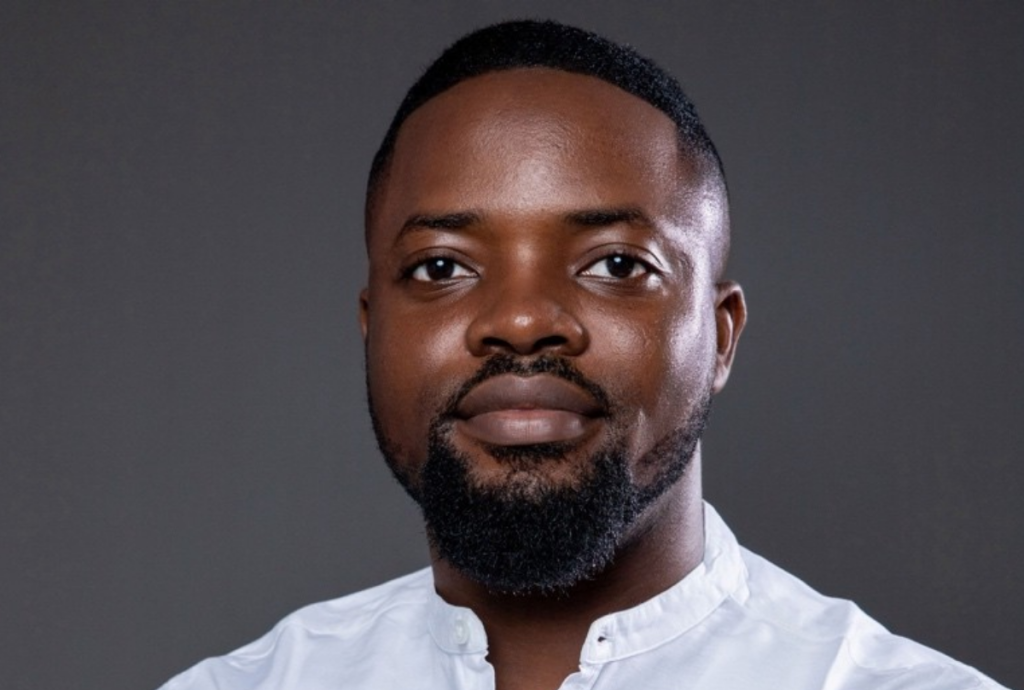
Ayotunde Alabi, chief executive officer and country manager for Luno Nigeria, , says the company is shifting beyond its retail crypto roots to sell digital asset infrastructure to banks, asset managers, and other institutions.
Ayotunde Alabi, chief executive officer and country manager for Luno Nigeria, says the company is shifting beyond its retail crypto roots to sell digital asset infrastructure to banks, asset managers, and other institutions. Image Source: Luno.

The stablecoin plan is not limited to one global token. Alabi said Luno plans to work on stablecoins backed by local currencies in different markets. According to him, the company is mulling plans for a Malaysian ringgit-backed stablecoin, as well as potential local currency stablecoins for African markets, including a possible naira-backed digital currency.

“There are two sister companies: GTXN and BlockTower. BlockTower is the vehicle Luno uses to issue stablecoins, and the plan is to issue stablecoins across different key African regions,” Alabi said. “We are thinking about Nigeria as well, with a naira-backed stablecoin. The infrastructure will allow us to use the different stablecoins to move [money] across borders in Africa.”

Through its local subsidiary BlockTower South Africa and a consortium of South African financial institutions, such as digital bank Lesaka Technologies, Luno issues and distributes ZARU, the South African rand-backed stablecoin launched in February.

For Luno, and like most digital asset businesses now focusing on institutional sales, selling to businesses and large enterprises creates a more predictable revenue stream, often with bigger ticket sizes. Unlike retail trading, institutional sales, especially when built around stablecoins increasingly pitched for mainstream finance, are less erratic.

The approach is similar to how several other global crypto companies evolved. Coinbase, the US crypto company, started in 2012 as a Bitcoin wallet, allowing users to buy and sell the cryptocurrency. By 2014, it had expanded into merchant processing for companies like tech original equipment manufacturer Dell and US-based hotel booking company Expedia, and a year later added an order-book trading exchange. 

Now, Coinbase offers Crypto-as-a-Service to banks, fintechs, and other businesses that want to add digital assets without building the trading and custody infrastructure themselves. 

Another example is Payward, the parent company of the US-based crypto exchange Kraken, which has paused its planned US IPO. In March, Payward launched Payward Services as a B2B infrastructure platform to offer institutional clients a single integration for stablecoin payments, trading, custody, funding, and settlement. 

In 2025, Payward expanded into the tokenisation sector by acquiring Backed Finance, the infrastructure operator behind xStocks, which allows crypto companies to distribute tokenised US stocks. Luno capitalised on this ecosystem by launching tokenised US stocks in 2025 through a direct partnership with xStocks.

Yet, to entice institutions, Luno also needs the network and ecosystem that has taken it years to build. A stablecoin is useful only if businesses can exchange it, settle with it, and convert it into local currency. Luno wants to connect the tokens to its exchange liquidity and GTXN’s regulated payout infrastructure.

For example, a Nigerian business paying a supplier in South Africa could use naira to acquire a rand-denominated stablecoin. Instead of moving money through several banks and converting naira into dollars before converting again into rand, the business could use the stablecoin as the settlement asset. GTXN would then facilitate the payout to the supplier in local currency, according to Alabi.

Luno would also need sufficient liquidity for customers to buy and sell the tokens, adequate local currency reserves to support redemption, and enough demand from businesses willing to use them. This is where retail distribution plays a key role.

Regulation would be its next moat. Luno needs regulatory approval in its key stablecoin distribution markets to build a business that attracts institutional interest. Luno is currently licenced as a crypto-asset service provider (CASP) in South Africa, while in Malaysia, it is registered with the Malaysian Securities Commission (SC) as a Recognised Market Operator for a Digital Asset Exchange (RMO-DAX). 

In Bermuda, Luno holds a Class F Digital Asset Business licence from the Bermuda Monetary Authority. In Nigeria, the crypto firm has been admitted into the country’s Securities and Exchange Commission’s (SEC) Accelerated Regulatory Incubation Programme (ARIP), allowing it to operate its crypto exchange and infrastructure service provider business under an approval-in-principle. 

Alabi said that the company’s Crypto-as-a-Service and stablecoin issuance offerings are already drawing interest from banks and asset managers.

“There is data available,” Alabi said. “We’ve seen a lot of interest, a lot of [people] knocking on the doors to say, ‘Look, we like what you’re doing. We’re seeing your engagements with regulators. We want to be a part of this.’ We’ve seen banks and asset managers come into the conversations, and a lot of things are unfolding very soon.” 

Luno sees institutional servicing as the strongest moat for its business, and stablecoins will play a key role. But importantly, retail is also evolving to remain a layer that deepens activity and informs that institutional buy-in. In February, Alabi told TechCabal that the company was pushing deeper into digital asset-based retail investment. That remains its long-term plan for retail customers as it aggressively chases enterprise clients.

Editor’s note: This article has been updated to clarify that Luno’s engagement in Malaysia is with two asset managers and does not involve Malaysian authorities.

True scale demands moving beyond surface-level integrations to robust execution. We’ve filtered the noise out of Moonshot 2026, optimising the conference strictly for high-calibre connections between startup founders, global financial operators, enterprise leaders and individuals rewiring Africa’s technical frameworks. Get 20% off Early Bird tickets for a limited time.
Moonshot mast head
Web hosting by Somee.com