×
Tech

After Koko’s collapse, Circle Gas faces Kenya’s carbon-credit test

Circle Gas has $67 million in carbon credits awaiting delivery

Circle Gas, the UK parent of Kenyan pay-as-you-cook liquefied petroleum gas (LPG) supplier M-Gas, reported $67 million in contracted carbon credits awaiting delivery and $57 million in cash prepayments in 2025, according to its financial statements. 

The company’s dependence on carbon-credit revenue exposes the financial risks facing Kenya’s clean-cooking businesses, where government authorisation can determine whether contracted credits deliver their expected value. 

The company’s accounts, filed in September, show the financial stakes. Circle Gas lost $39.3 million in 2025, held $1.1 million in cash at year-end and reported net liabilities of $156.7 million. It needs about $28 million in new funding to finance its growth plans.

Carbon credits are central to the economics of clean cooking businesses such as M-Gas. The company supplies LPG in small, affordable amounts with smart meters so households can pay as they cook. Revenue from the resulting emissions reductions can help support that model. Koko Networks, another Kenyan clean-cooking company, entered administration after the government declined to authorise the carbon-credit sales on which its business depended.

Circle Gas’s annual report says it received a “Letter of Acceptance” confirming that its carbon-credit projects met eligibility criteria and could proceed to apply for a “Letter of Authorisation.”

M-Gas announced in January 2026 that its clean-cooking carbon project had received a Letter of Approval. The report does not clarify whether this is the same document it calls a Letter of Acceptance.
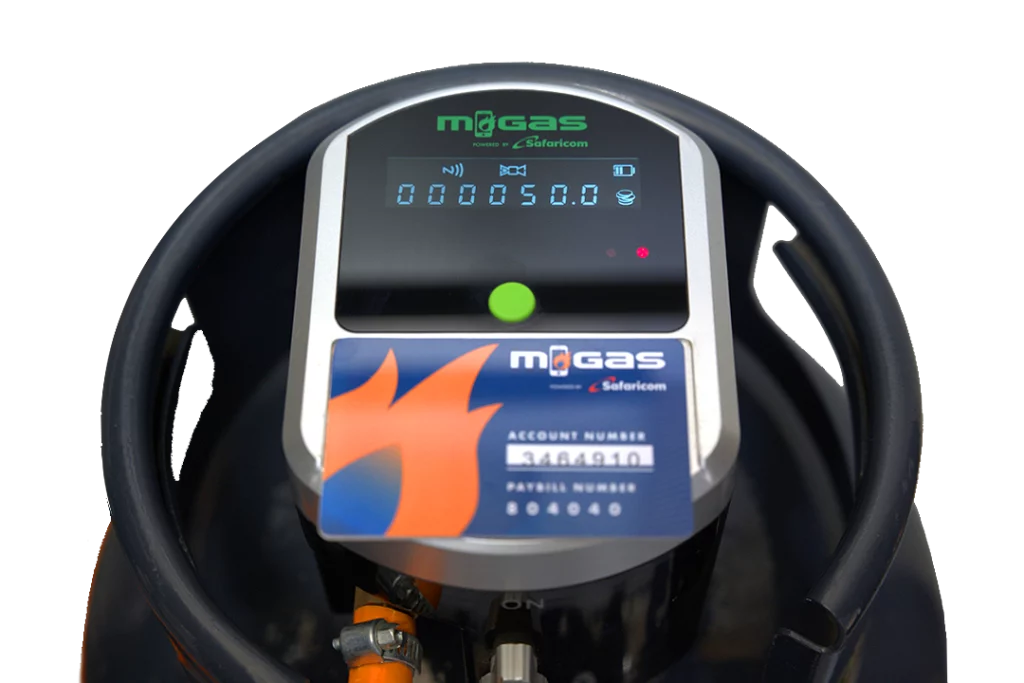

M-Gas uses smart-meter technology powered by Safaricom to measure LPG consumption, allowing customers to pay as they cook. Image: M-Gas

Kenya’s carbon-market rules distinguish project approval from authorisation to transfer credits internationally. Under the relevant framework, the final authorisation requires government approval and determines whether specified emissions reductions can be transferred abroad.

Circle Gas did not respond to a request for comment.

The value of carbon credits

Circle Gas reported $67 million in contracted carbon credits yet to be delivered as of the end of 2025, and $57 million in cash already received as prepayments against carbon-credit contracts. The first figure represents credits awaiting delivery, while the second is money buyers have already paid.

The accounts do not disclose how much of the contracted portfolio depends on the outstanding authorisation or how much of the prepayments remains available.

Circle Gas says authorised credits can command significantly higher prices than credits sold in advance. It has not disclosed the expected premium. The company also excludes the higher value from its financial projections, leaving the potential upside outside its current funding assumptions.

Circle Gas grew revenue to $40.8 million in 2025 from $36.1 million, but remained loss-making, with a $39.3 million loss after tax. Its cash reserves fell to $1.1 million, while net liabilities climbed to $156.7 million from $116.5 million.

The company says it needs about $28 million to fund its 2026 growth plans. Without additional funding, it expects to limit investment and remain stagnant.

“At the date of approval of these financial statements, the additional third-party funding of approximately US$28.0m necessary to finance continued growth funding for the base case in 2026 is yet to be fully secured, and there is no certainty that funding will be available to the Group (Circle Gas),” the statement said. 

The losses and funding needs cannot be attributed solely to the outstanding authorisation. But the delay leaves a potentially more lucrative source of carbon revenue uncertain as Circle Gas seeks new capital. 

Koko’s carbon debt

Koko Networks built a business selling subsidised bioethanol stoves and fuel to low-income households, relying on carbon-credit sales to cover part of its operating costs. When the Kenyan government declined to authorise those sales, the company lost access to a revenue stream it needed to sustain the business.

Koko shut down in January 2026, laying off more than 700 employees. Its Kenyan and UK entities entered administration in February. The administrators now face the task of recovering money owed to creditors, with the carbon credits held by its UK arm a central asset. Without a sale, FirstRand Bank is owed $60 million, while other unsecured creditors are owed about $171 million.

Koko’s collapse shows how a clean-cooking business can accumulate substantial debts when it cannot sell the carbon credits expected to fund its operations. 

The government rejected Koko’s application in early February 2026, with Trade Cabinet Secretary Lee Kinyanjui saying the volume of credits sought could have exhausted Kenya’s allocation for international transfers, leaving other projects in agriculture and manufacturing with little room to sell their credits abroad. 

Unlike Koko Networks, Circle Gas has not had its authorisation request rejected. M-Gas announced that its project had received a Letter of Approval. However, Circle Gas’s accounts indicate it is still seeking a Letter of Authorisation and do not disclose how much of its contracted carbon credits depends on it.

Koko is the clearest warning of what is at stake:  carbon credits may be recorded as assets, contracted to buyers and used to secure financing, but they cannot generate the expected cash if the company cannot sell them.

Kenya’s carbon-credit rules give the government control over which emissions reductions can be sold abroad, leaving companies exposed to decisions that can affect their revenues and debts. 

Circle Gas secured earlier approval for its project but is still seeking authorisation, leaving the value and delivery of some contracted credits uncertain. 

True scale demands moving beyond surface-level integrations to robust execution. We’ve filtered the noise out of Moonshot 2026, optimising the conference strictly for high-calibre connections between startup founders, global financial operators, enterprise leaders and individuals rewiring Africa’s technical frameworks. Get 20% off Early Bird tickets for a limited time.

§

CrissCross, the South Africa-headquartered cross-border payments infrastructure company, has secured an undisclosed investment from Circle Ventures, the corporate venture arm of Circle Internet Group, the company that issues USD Coin (USDC), a digital stablecoin.

The investment, made through Stitch Group, CrissCross’s parent company, will help the company expand its local payment connections and liquidity, build more stablecoin settlement capabilities for enterprise customers, and grow the team supporting clients across the continent.

Stablecoins are increasingly being used to move money across borders, making them a growing part of Africa’s payments infrastructure. Circle’s investment marks its second notable bet on the sector in 2026. In July, it invested in Nigerian fintech Flutterwave as the company expanded USDC settlement across its payments platform, allowing businesses to collect payments locally and settle in USDC. s.

“Africa’s cross-border payments market is massive, complex, and underserved,” James Cope, general manager at CrissCross, said in a statement. “Circle Ventures’ investment validates what we’ve been building: infrastructure that can handle that complexity at scale.”

Lex Campbell and Byron Coetsee founded CrissCross to make cross-border payments more efficient for enterprise businesses operating in African markets. The company was acquired early by Stitch and now sits within Stitch Group, the South Africa-based payments group. CrissCross provides businesses with a single application programming interface (API) to collect money, make payouts, manage funds and exchange currencies across African markets. 

For collections, CrissCross lets customers pay merchants using familiar local methods such as bank transfers, mobile money and cards. For payouts, businesses can send individual or bulk payments directly to local bank accounts and mobile wallets. Its treasury tools let companies manage funds across multiple currencies, while its foreign exchange infrastructure lets them convert between local currencies, US dollars, and euros.

CrissCross connects blockchain-based settlement to local fiat payment networks. A business can move value between markets using stablecoins, while the recipient can receive local currency in a bank account. The company says it chooses between stablecoin and fiat rails based on a client’s requirements. It makes money from the payments and currency conversions it processes for clients, and says its pricing varies depending on the markets, payment methods, and services each customer uses.

“Stablecoins help funds move between markets quickly and transparently, and the money is delivered in local currency to the recipient’s bank account or mobile wallet,” the company said in a statement shared with TechCabal. “We use stablecoin or fiat rails depending on what each client needs for speed, cost and compliance.”

CrissCross is trying to close the gap between global stablecoin liquidity and local payment infrastructure. In October, CrissCross partnered with Velocity, a stablecoin payments and treasury platform, to connect institutional on-chain liquidity with local collections, payouts and FX. The partnership aimed to connect global stablecoin liquidity to local bank accounts and payment rails.

Sub-Saharan Africa received more than $205 billion in on-chain crypto value between July 2024 and June 2025, up 52% from the previous year. As crypto activity grows, so does demand for infrastructure that connects digital assets to local payment systems and enables cross-border payments.

“We’re excited to support CrissCross as they bring stablecoin-powered payments infrastructure to scale across African markets — some of the most complex and underserved corridors in the world,” said Brian Schultz, vice president of corporate development and ventures at Circle.

CrissCross says it currently operates across more than 30 markets spanning West, Central, East, Southern and North Africa, including both CFA franc zones, and supports more than 20 currencies. Its customers include multinational enterprises, financial institutions and platforms that need to move money across complex African payment corridors. The company wants to become the infrastructure that lets global businesses treat Africa as one connected market rather than a collection of separate payment systems.

“We want global businesses to find it as easy to collect and pay out across African markets as anywhere else they operate,” it said. “A company operating in Nigeria, Senegal or Kenya should be able to do it through the same infrastructure, with predictable settlement and full visibility over its funds. More enterprises are building their growth plans around African markets, and we want CrissCross to be the payments infrastructure they use to do it.”

Stablecoins are becoming the layer underneath payments for African payments companies. In June, Flutterwave announced an investment from Ripple as part of its Series E and said it would integrate RLUSD, Ripple Payments, and the XRP Ledger into its payment infrastructure. It has also partnered with Polygon and Tempo to build out stablecoin settlement infrastructure. 

Onafriq, which operates across more than 40 African countries, has taken a similar route. In February, it partnered with Conduit to use stablecoins such as USDC to fund accounts and rebalance treasury holdings, and announced another partnership in July with digital-asset infrastructure provider Privy to develop regulated stablecoin-powered payment services for financial institutions.

Yellow Card has shifted its focus towards businesses, providing stablecoin payment infrastructure, fiat settlement rails, custody, and local stablecoin issuance. Once associated with crypto trading, dollar-backed stablecoins are now being positioned as a way for businesses to settle transactions and move money across borders.

True scale demands moving beyond surface-level integrations to robust execution. We’ve filtered the noise out of Moonshot 2026, optimising the conference strictly for high-calibre connections between startup founders, global financial operators, enterprise leaders and individuals rewiring Africa’s technical frameworks. Get 20% off Early Bird tickets for a limited time.
§

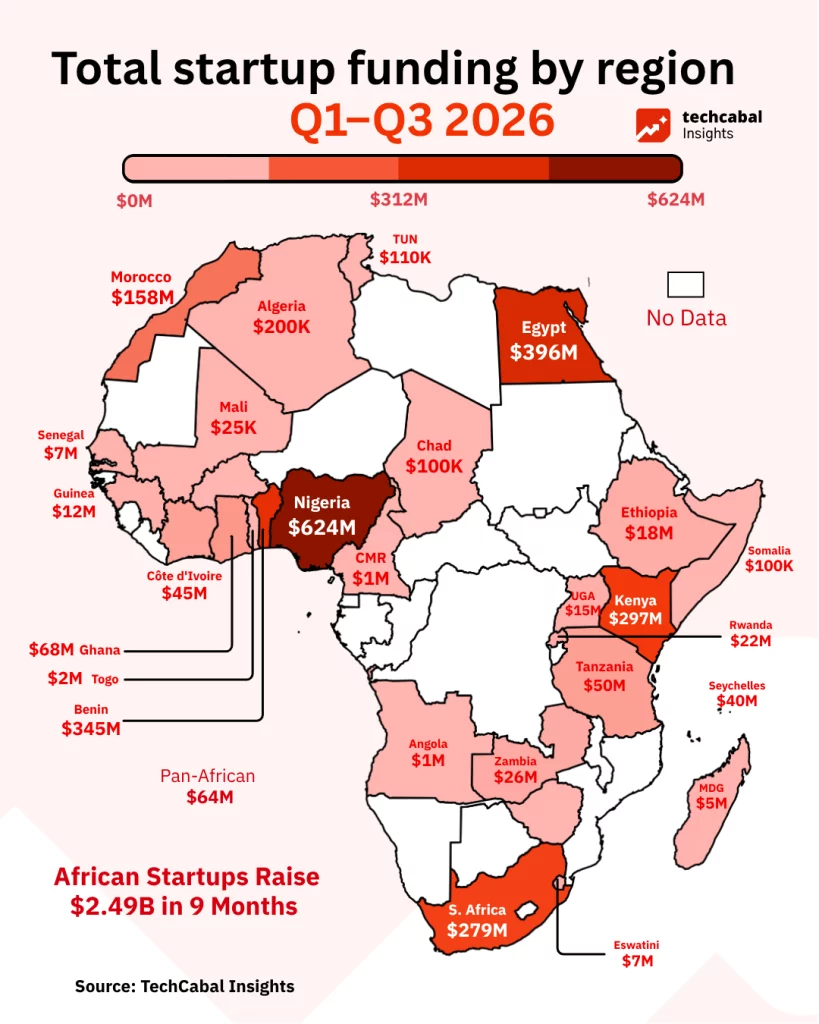
In the first nine months of 2026, African startups raised $2.49 billion across 315 disclosed deals, representing 7.8% year-on-year growth from the $2.30 billion raised across 403 disclosed deals in the same period in 2025.

While overall transaction volume dropped in the first half of the year, funding activity rebounded sharply in Q3 2026. Q3 alone brought in $1.025 billion across 167 deals, up from $785 million across 149 deals in Q3 2025, driven by stronger deal flow and larger growth rounds.

Energy, fintech, and clean tech lead big deals

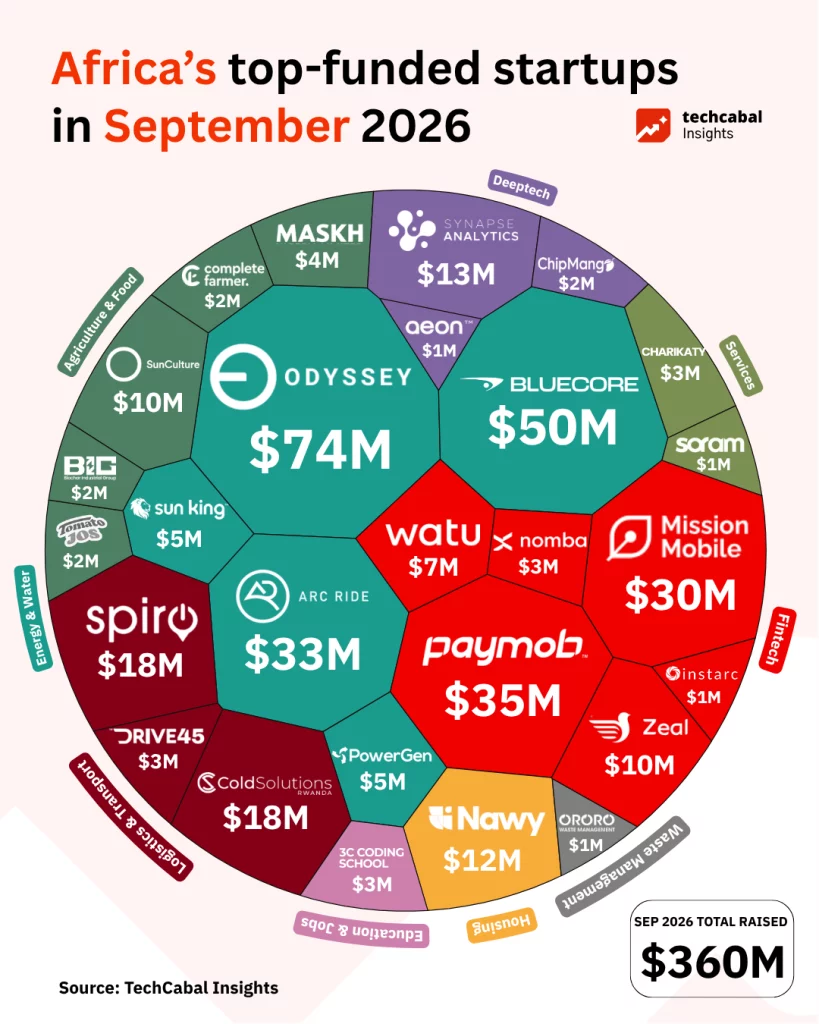
September kept up the Q3 momentum, with investors directing relatively large capital checks into energy infrastructure, mobility, and digital payments platforms.

  • Bluecore Energy (Ghana) raised a $50 million seed round, backed by Slauson & Co., Harlem Capital, Chris Larsen, Collab Capital, HartBeat Ventures, Tesla, Uber, and Amazon, to develop maritime nuclear technology.
  • Odyssey Energy Solutions (Nigeria) secured $74 million in combined capital, including a $47 million debt facility from BII, BIO, Cygnum Capital, and TripleJump, alongside $27 million in equity from Broadscale Group, FMO, and Al Mada Ventures.
  • Paymob (Egypt) raised $35 million in Pre-Series C funding led by Mubadala and EBRD.
  • Mission Mobile (South Africa) pulled in $30.7 million from DN Invest for device-financing infrastructure.
  • ARC Ride (Kenya) completed a $33.3 million round ($23.3M equity led by Novastar Ventures, Norrsken22, and IFC, plus $10M debt) for its e-mobility battery-swapping network.
  • Spiro added $18 million in debt from the Africa Go Green Fund, matching an $18 million debt round raised by Cold Solutions (Kenya) from Cygnum Capital.
  • Synapse Analytics (Egypt) raised $13 million in Series A funding led by Partech, while Nawy Now (Egypt) secured a $12.3 million debt facility.
  • Zeal (Egypt) and SunCulture (Kenya) each pulled in $10 million.

Top funding destinations: Nigeria and Egypt lead

Nigeria remains Africa’s top funding destination so far in 2026, pulling in $624 million across the first nine months. Egypt ranks second with $396 million, followed by Benin ($345 million), Kenya ($297 million), and South Africa ($279 million).

LPs inject $3.08B into African fund managers

Capital is also flowing steadily into fund managers (GPs)  deploying capital on the ground.

According to our State of Tech in Africa H1 2026 Report, LPs committed over $1.7 billion to fund managers in the first half of the year. Q3 2026 added another $1.23 billion in new commitments, bringing total capital raised by African fund managers to $3.08 billion between Q1 and Q3 2026.

Major Q3 2026 fund closes

  • Ninety One closed its Africa Credit Opportunities Fund 3 at $404 million to scale private debt financing.
  • Airnergize Capital (South Africa) reached a $239 million final close for its Clean Energy Fund, backed by DBSA, Standard Bank, and Nedbank.
  • Acumen Capital Partners reached a $90 million second close for its Resilient Agriculture Fund (ARAF) and secured $12 million for ARAF II.
  • Ventures Platform completed an $84 million second close for its Pan-African Fund II, backed by Norfund and the European Bank.
  • CardinalStone Capital Advisers hit a $76 million first close for its West Africa SME growth fund.
  • AgDevCo achieved a $49 million first close targeting early-stage East African agritech.

Fund managers have secured over $3.08 billion in new LP commitments between Q1 and Q3 2026 across climate tech, private credit, and early-stage equity. While this fresh dry powder sets the stage for a strong finish to the year, founders must adapt their fundraising strategies to access it. Securing these new funds requires startups to look beyond traditional equity, build capacity for venture debt, and demonstrate the robust unit economics that today’s capital allocators demand.

Web hosting by Somee.com