For hundreds of African divorcees, widows, and single parents, returning to the dating pool means facing a wall of silent shame and public judgement. Late one night, corporate finance analyst Tega Ogaga watched an online comment section brutally attack a single mother of three who dared to ask for love again. Disturbed by the cruelty, he decided to build an answer: Runo—a trust-first relationship platform designed specifically for those brave enough to search for a second act. In his latest feature, JOHN ADOYI explores the unspoken taboos surrounding second-chance romance in Africa, and how one founder is building a digital sanctuary free from apology or explanation.
Late one night in 2025, Tega Ogaga sat in the quiet of his room, staring at a laptop screen that refused to cooperate.
As a corporate finance analyst, he was used to complex numbers, but a colleague had passed along a broken financial model, and Ogaga had brought the problem home. When his own attempts to fix the figures hit a brick wall, he put his work aside and picked up his phone to clear his head.
Scrolling through Facebook, he came across a post on a community matchmaking page. A single mother with three children had written a short, vulnerable message explaining that she was ready to start over and hoped to find a partner.
Then Ogaga opened the comment section.
“What I saw there, some of them were just horrible,” Ogaga recalls. Stranger after stranger had lined up to mock her, questioning why any self-respecting man would shoulder the financial and emotional burden of raising another man’s children. One comment in particular burned itself into his memory: “Why should I become their father? Why did their father run?”
Disturbed, Ogaga spent the next few hours down an unexpected digital rabbit hole, searching Facebook matchmaking groups for similar posts by widows, widowers, divorcees, and single parents. Everywhere he looked, the pattern repeated itself: human longing met with callousness, vulnerability met with public humiliation.
It raised a quiet, uncomfortable question: What happens when someone who has buried a spouse, survived the painful breakdown of a marriage, or raised a child alone decides they are finally ready to start dating? If putting oneself forward means facing ridicule for their past, most will simply retreat into the shadows and choose loneliness instead.
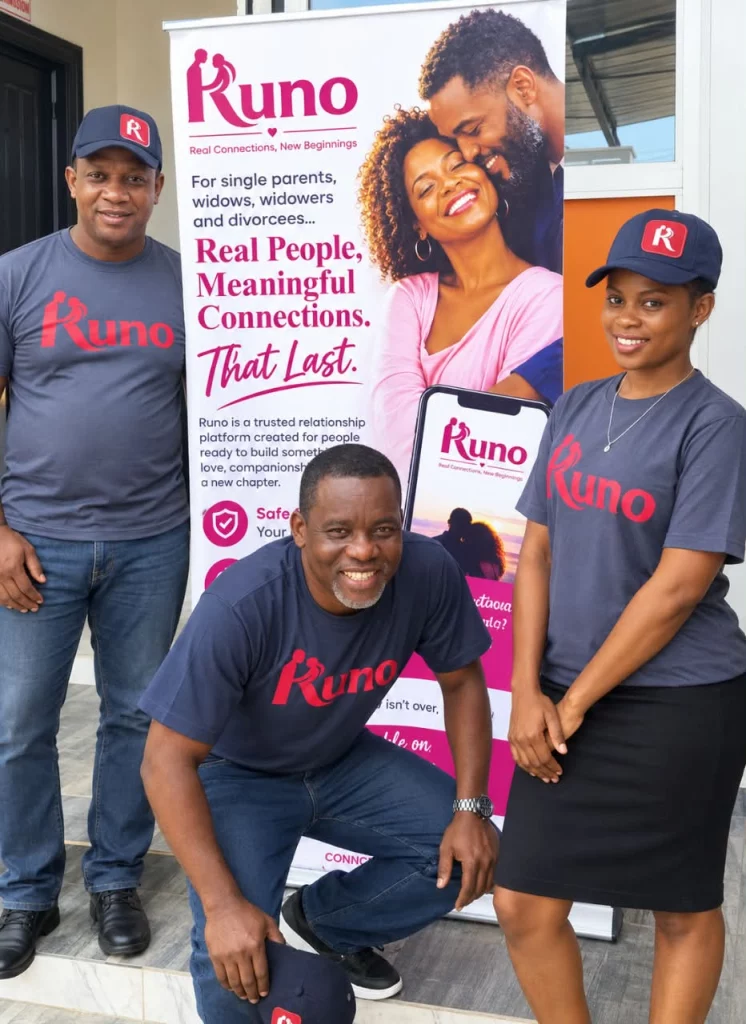
That realisation gave birth to Runo: a dating and relationship platform engineered specifically for widows, widowers, divorcees, and single parents. On Runo, members can meet without having to explain, defend, or apologise for their decision to start again.
Scheduled to launch on October 9, beginning in Lagos, the app is a deliberate attempt to rewrite the rules of second-chance dating in Africa.
The heavy burden of starting over
For people in this demographic, re-entering the dating world is rarely straightforward. You do not simply show up as an individual; you carry the reality of your past into every introduction. There are children to explain, previous vows to discuss, and, for grieving spouses, a quiet sorrow that never completely leaves the room.
As Ogaga began interviewing men and women across these groups, he realised the problem ran far deeper than nasty Facebook comments. The fear of judgement had bred a culture of silent shame. One widow he knows confessed that she avoids telling acquaintances she is looking for a husband, preferring isolation to the unsolicited opinions that inevitably follow.
There was also a glaring mismatch in the market. Conventional dating apps are built for speed, youth, and casual encounters. But adults who have navigated life’s harsher chapters approach romance with caution and clear intention. The tools available to them were simply never designed for their reality.
For Mercy, a 33-year-old mother living in Lagos, that gap is not an abstract market concept—it is her daily existence. Two years ago, five years into their marriage, her husband died after a prolonged illness, leaving her alone with their two young children.
“It can be very lonely,” she says quietly. “I really liked spending time with my husband while he was alive. Unfortunately, I am alone for now.”
Mercy had dabbled on Tinder before her marriage, mostly out of youthful curiosity. She did not meet her husband there, and she certainly does not view it as a place to find a serious partner today. Her greater worry is the predatory nature of unregulated online spaces, where single mothers are often viewed as vulnerable or desperate.
“A lot of people are looking for good partners and friends, but they are scared of meeting the wrong people,” she says.
The desire for genuine companionship crosses generations. Mercy’s 49-year-old aunt has been searching for a partner since her husband passed away a decade ago. Desperate to connect with someone decent, she even resorted to calling into late-night radio matchmaking programmes, only to encounter men with dishonourable motives.
“If this one can work out,” Mercy says of Runo, “I can introduce her to it.”
Academic research confirms the steep social penalties attached to starting over in Nigeria. A 2024 study conducted in Ife-East, south-western Nigeria, by Ayomide Oluseye, Philippa Waterhouse, and Lesley Hoggart examined the lives of 24 young unmarried mothers alongside 10 key community informants. The researchers found that pervasive social stigma heavily restricted how these women navigated their relationships and dating lives.
A separate 2017 study on divorce and remarriage across Lagos and Abuja revealed a sharp gender double standard: divorced women faced significantly harsher societal condemnation and barriers to remarrying than divorced men.
For Ogaga, these studies confirm that his target audience is not looking for another generic dating app. They need a space where their life circumstances are understood from the very first click.
The typical Runo user, he explains, is a 44-year-old widow who works hard, pays her bills, and cares for her children, but spends her weekends in a quiet house, wishing she could share her life with someone again—yet terrified of the humiliation that usually accompanies the search.
An architecture built on trust
Runo is designed specifically for adults aged 28 to 65—an age bracket chosen deliberately to screen out casual seekers and attract people who approach dating with maturity.
“Our demographic are people who want an opportunity to start again,” Ogaga says. “They are very intentional.”
That intentionality shapes the software itself.
When members sign up, they are encouraged to register using a mobile phone number. In Nigeria, where SIM cards are linked to official identification databases, this provides an immediate layer of personal accountability. Users build detailed profiles outlining their age, marital history, occupation, religion, and family structure. They specify the exact number and ages of their children, whether they are open to dating someone who already has kids, and the specific qualities they hope to find in a partner.
Boundaries are strictly enforced. If a 60-year-old sets their preference for partners aged 45 to 55, the algorithm will never show them profiles outside those parameters.
While the app uses a familiar swipe interface, it eliminates the unsolicited messaging common on other platforms through a strict mutual-match requirement: no one can send a message unless both parties have explicitly liked each other’s profiles.
“If I’m swiping and I like this person’s profile, that person gets a profile alert,” Ogaga explains. “If he or she looks at my profile back and doesn’t like mine, then I can never send a message to that person.”
Privacy is equally paramount. Members can browse anonymously without displaying photographs, choosing the exact moment they wish to reveal their pictures to a mutual match. Optional identity verification grants a badge to users who submit government-issued IDs, while a reporting system allows members to flag suspicious accounts for investigation and removal.
“The most important feature I want to build into Runo because of our demographic is that feature called trust,” Ogaga says. “The people in this demography are very sensitive. Some of them have been beaten once, some twice.”
The platform operates on a freemium model. Basic access is free, while a Premium subscription costs ₦7,500 a month and a VIP tier is priced at ₦75,000 annually. Advanced features, such as in-app audio and video calls, utilize “RUNC,” the platform’s digital currency, which can also be used to send virtual gifts.
Rooting in community
Rather than launching with aggressive social media ads, Runo is taking a grassroots approach to user acquisition.
Ogaga and his team are reaching out directly to churches, imams, grief counsellors, divorce lawyers, and community support groups for single parents and widows. They are also joining WhatsApp groups where these demographics already gather to share advice and support.
This strategy serves two purposes: building deep trust and maintaining control over who enters the ecosystem during its fragile early days.
“We want to get these people’s trust first before we start doing a massive social media campaign,” Ogaga says. “Because a massive campaign could bring an influx of people, and we might struggle to control it.”
The approach is already showing promise. Within ten days of opening its waitlist—without spending a single naira on paid advertising—Runo gathered over 200 sign-ups.
Partnering with community leaders provides an initial layer of screening, as counsellors and religious leaders already know the individuals they serve. However, Ogaga is realistic about the cultural pushback ahead. In several Nigerian cultures, long-standing traditions discourage widows from ever remarrying.
“There are cultures in Nigeria where a widow is not allowed to remarry,” he acknowledges. Rather than avoiding these communities, Runo plans to address traditional taboos through public education, open dialogue, and storytelling as the company expands.
Building a lasting institution
Ogaga spent nine months preparing Runo for market: six months establishing the company’s institutional framework and three months on software development.
The result of those early months was a six-volume, 500-page operational blueprint covering brand identity, product requirements, market analysis, and investor readiness. For Ogaga, this was not an exercise in bureaucracy; it was about building something meant to endure.
“I want to build a social institution,” he says flatly. “And that’s what I’m trying to do.”
That preparation has also shaped his capital strategy. Although Runo is structured for eventual venture backing, Ogaga has deliberately chosen not to pitch investors yet. He wants to prove product-market fit and generate operational revenue first.
“When I get traction and it’s time to bring in a senior investor, I think I will be in a better position to negotiate,” he explains. “Because they are not coming in to help me build a startup; they are coming into a business that is already working.”
For its first year, Runo is targeting 50,000 users in Nigeria before establishing regional hubs in Nairobi, Johannesburg, and Kigali. His three-year model projects a user base of 250,000, with an estimated 4% paid subscriber conversion rate yielding a valuation of $4.09 million based on a 5x ARR multiple.
Yet, despite his background in corporate finance and financial modeling, Ogaga knows that Runo’s ultimate value cannot be captured on a balance sheet.
“Our greatest success is going to be determined by the number of people who are no longer on Runo, who left because they found what they wanted,” he reflects. “That will really tell me I am not wasting my time or energy.”
True scale demands moving beyond surface-level integrations to robust execution. We’ve filtered the noise out of Moonshot 2026, optimising the conference strictly for high-calibre connections between startup founders, global financial operators, enterprise leaders and individuals rewiring Africa’s technical frameworks. Get 20% off Early Bird tickets for a limited time.