×
Tech

Flutterwave CEO on why African fintechs want to become banks

Flutterwave CEO on why African fintechs are trying to become banks

In April, Flutterwave, a pan-African fintech unicorn, secured a national microfinance banking licence through its acquisition of open banking startup Mono. It joined a growing group of Nigerian fintechs moving into regulated banking. In January, Paystack acquired Ladder Microfinance Bank, while Moniepoint secured a microfinance banking licence in 2025.

African fintechs are moving from only processing payments to holding deposits, providing credit and offering other banking services. For Olugbenga “GB” Agboola, cofounder and CEO of Flutterwave, African fintechs are becoming banks because payments alone are no longer enough.

Speaking at Moonshot in Lagos on Wednesday, Agboola said Flutterwave’s decision to obtain a national microfinance banking licence was driven by the need to control more of the infrastructure behind its payments business.

“What we’ve seen is you cannot provide a great payment experience if you don’t control the entire stack, or at least a big piece of the stack,” Agboola said. “And in most of those large stacks, it’s easy to source a third party who does not share the same level of focus that you have.”

Flutterwave has processed more than $40 billion in lifetime payments, giving it a large existing payments business to build its banking strategy around. The company has also said that more than 2 million businesses use its platform. Agboola said the scale of the payments business also exposed the limitations of relying on third-party financial institutions. If a partner bank goes down, parts of Flutterwave’s payment infrastructure can go down with it.

“We didn’t choose to do banking for the sake of banking,” Agboola said. “We chose to do banking to create more depth for our customers.”

The move into banking also gives Flutterwave a path into lending, an area where the company believes its existing transaction data could give it an advantage. Agboola said Flutterwave can see how businesses and consumers use its payment infrastructure, including when customers attempt transactions without sufficient funds or when businesses have receivables but need working capital immediately.

However, Flutterwave’s lending strategy is not immediately focused on becoming a mass-market lender. Agboola said the company is starting with liquidity and working-capital infrastructure, including pre-funding payouts for companies that need to make payments in Africa before receiving their own funds.

In June, Flutterwave raised a Series E round at a $3.25 billion valuation after Ripple invested an undisclosed amount in the company. The partnership also integrated Ripple’s RLUSD stablecoin into Flutterwave’s payment infrastructure. 

The deal was part of a larger stablecoin strategy that followed the company’s partnership with Turnkey and Nuvion to launch stablecoin balances and embedded wallets supporting USDC and USDT. In June, it also partnered with Tempo to build stablecoin-powered payment and settlement infrastructure for African payments.

Agboola said the company is seeing businesses encounter stablecoins as a practical payment option, particularly when paying international suppliers.

“We’ve built what I call the largest deployment of stablecoins in Africa, where we support all the blockchains and stablecoins,” Agboola said.

The expansion is happening against a backdrop of rising competition between fintechs and traditional banks for control of customers’ financial relationships. Flutterwave says it currently operates across more than 35 countries and has more than 50 global licences.
§

Bluebulb has launched a treasury management platform to help African businesses oversee cash, currencies, and international payments from a single dashboard, as the fintech seeks to expand beyond moving money.

The company introduced Orbita at Moonshot by TechCabal 2026 in Lagos, targeting finance teams that rely on multiple banking portals and spreadsheets to track funds across accounts and markets.

The platform combines multi-currency wallets, cross-border payments, payment tracking, and treasury analytics. Bluebulb said it would help businesses monitor liquidity and cash flow while reducing their dependence on disconnected financial systems.

The launch addresses an operational challenge for companies expanding internationally: establishing where their money sits, which payments remain outstanding, and how much cash is available to meet approaching obligations.

Paying suppliers in different countries can require finance teams to reconcile information across banks, currencies and payment networks. That fragmentation can make it harder to assess a company’s financial position or respond quickly to funding needs.

“Africa is not short of ambitious businesses. What we need is financial infrastructure that can match that ambition,” Ola Daramola, Bluebulb’s chief executive and co-founder, said ahead of the event.

Daramola said the company wanted to move beyond payments by giving businesses greater visibility and control over their finances as they compete internationally.

Orbita is intended to bring those functions together. Alongside initiating and tracking payments, finance teams can use the platform to monitor balances across currencies and analyse cash movements, according to Bluebulb.

The distinction is significant for businesses operating across several markets. A completed payment shows that money has moved; treasury management provides a broader view of available funds, upcoming commitments and exposure to currency movements.

Bluebulb’s proposition rests on making that information easier to consolidate and act on. For customers, the test will be whether a single platform can replace enough manual reconciliation and fragmented reporting to make managing international operations simpler.

§

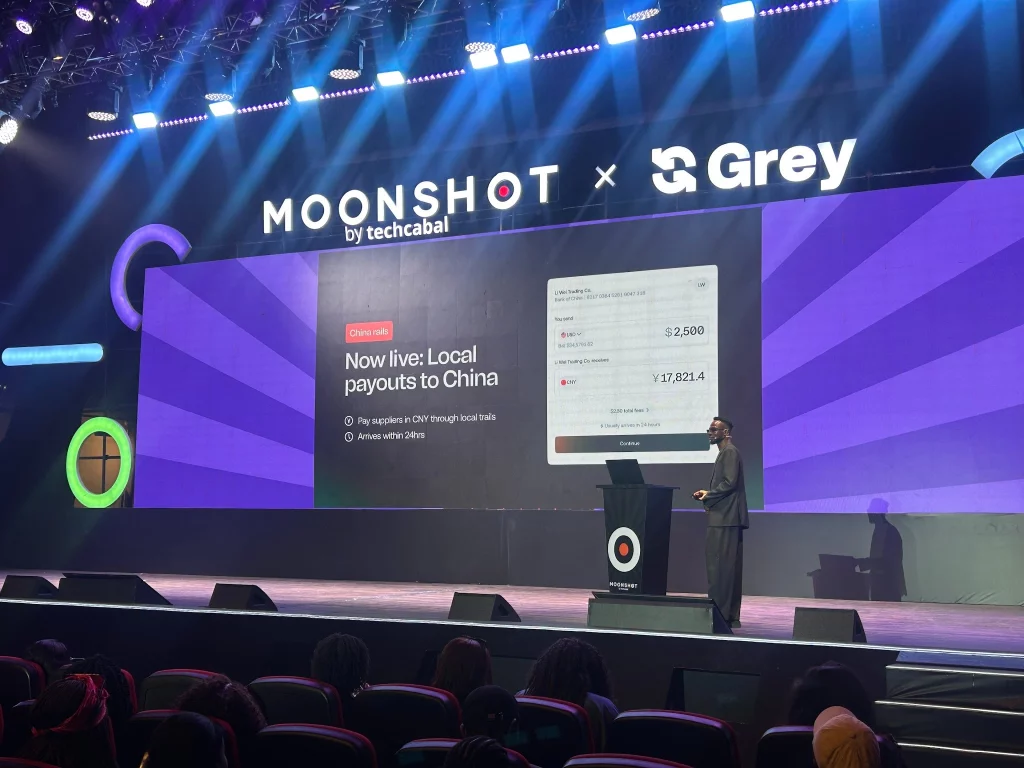
Grey is offering businesses direct payments to Chinese bank accounts to reduce currency conversions and intermediaries involved in paying overseas suppliers, co-founder and chief operating officer Femi Aghedo told Moonshot by TechCabal in Lagos.

Demonstrating the service, Aghedo showed how Grey Business customers could convert dollar or stablecoin balances into renminbi and pay suppliers in China. The feature targets businesses whose international payments can pass through several banks and currencies, adding costs and delaying settlement.

For African importers buying from Chinese manufacturers, the service offers a more direct route to suppliers in one of the continent’s most important trading markets.

The expansion comes as Grey builds its business offering alongside its consumer platform. The company says it serves more than 3 million users across 70 countries and supports payouts to more than 170 destinations.

Stablecoins accounted for the largest share of Grey’s cross-border flows. Image source: TechCabal

Grey Business, launched in February, had processed $61.4 million in payment volume by June, according to the company. Stablecoins accounted for the largest share of its cross-border flows.

That mix offers an indication of how customers use digital currencies in their day-to-day financial operations. Grey allows businesses to hold USDC and USDT, transfer them, and convert them into local currencies when needed. The China payment feature extends that offering by allowing customers to convert balances into their suppliers’ required currency.

Aghedo’s demonstration also covered the more routine demands of managing a business account. Companies can hold dollar balances, issue prepaid expense cards to employees and control or freeze their use. They can make bulk payments by uploading a spreadsheet, using the exchange rates available at the time, or connect their own systems to Grey through application programming interfaces that automate payments.

Together, the tools position Grey Business as a service for managing international spending and company payments, as well as moving money across borders.

The commercial case rests on reducing friction in collecting revenue, holding funds, and paying suppliers. For a business earning in one currency and purchasing stock in another, each additional conversion or intermediary can erode its margin.

Aghedo’s presentation put the China service at the centre of that argument: businesses should be able to move from a dollar or stablecoin balance to a supplier’s bank account with fewer steps in between.

Web hosting by Somee.com