×
Tech

The 20-metre neobank: How Mukuru is solving the gap between receiving cash and spending it

The 20-metre walk that explains Juan Seco’s vision for Mukuru

Why does a 20-metre walk in Harare explain the future of African fintech? When Juan Seco left Wall Street private equity for African tech, he realised the biggest gap wasn’t complex financial software—it was what happens after a remittance arrives. From auditing American Express in New York to building JumiaPay and scaling Mukuru’s neobank infrastructure across Southern Africa, Seco joins PATHISANI MOYO in our latest edition of Coffee With…

A few days before speaking with Juan Seco, Chief Growth Officer and Managing Director for East Africa at Mukuru, a digital financial services company, I found myself reflecting on a conversation with my 76-year-old mother.

She lives in Harare; I live in Johannesburg. Having transferred funds to her via Mukuru, I called to check if the money had arrived safely. Her response was characteristically direct: “Mntanami (my son), don’t ever send me money through your friends again.”

The funds had landed directly on her mobile phone, allowing her to collect the cash in person after a brief 20-metre walk. That modest 20-metre stroll captures the core philosophy behind Mukuru’s expansion far better than any corporate presentation.

The 20-metre lesson

For the Spanish-born executive, who spent years advising tier-one financial institutions in New York before relocating to Nairobi, the future of African fintech is not about crafting hyper-complex financial instruments. It is about eliminating the friction that hinders how people receive, store, move, and spend their money.

That principle underpins Seco’s definition of South Africa-headquartered Mukuru as a “remittance-led neobank.” 

It helps explain why a company best known for helping migrants send money home is fast moving into everyday digital financial services, from wallets and cards to payments and banking infrastructure.

Today, Mukuru operates across more than 60 countries, serving 17.6 million customers through a vast physical and digital payout network across Southern and East Africa. 

Seco’s path to African financial infrastructure was anything but linear. Born in Madrid, he spent his childhood between France and Luxembourg before studying finance and international business at McGill University in Canada.

He began his career at PwC in Spain, auditing financial institutions such as American Express and Prudential, before transferring to New York to work in private-equity mergers and acquisitions. On paper, it was a textbook corporate career; in practice, it was an exhausting routine.

The turning point arrived when Seco and his wife—a Colombian corporate lawyer who grew up in Kenya—welcomed a daughter, followed quickly by twins. Managing three children under three alongside two high-powered corporate careers proved unsustainable.

“We found ourselves working crazy hours with three kids under three,” Seco recalls. His wife posed a decisive question: “You’ve been unhappy for years doing work you aren’t passionate about. Why not make a change?”

The answer was Nairobi, the Kenya capital city, where Seco took what he describes as a huge pay cut to join Jumia, Africa’s e-commerce trailblazer. It was a dramatic move from the world of New York finance into one of Africa’s most ambitious technology companies at the time.

He would spend roughly a decade in the Jumia ecosystem, working across technology, commerce, and financial services. It was there that Seco began to see African financial infrastructure differently.

The problem that changed how he saw African fintech 

As Jumia’s chief financial officer (CFO), he encountered a problem that looked mundane but had enormous implications. The company operated across multiple African markets, and customers often paid in cash. Cash-on-delivery was expensive and operationally painful. Digital payments, by contrast, could make the business more efficient.

But building those payment connections was not simple. The same technology team operating across numerous countries and business lines was repeatedly building integrations with different mobile-money systems, including M-Pesa, Kenya’s pioneering mobile money service.
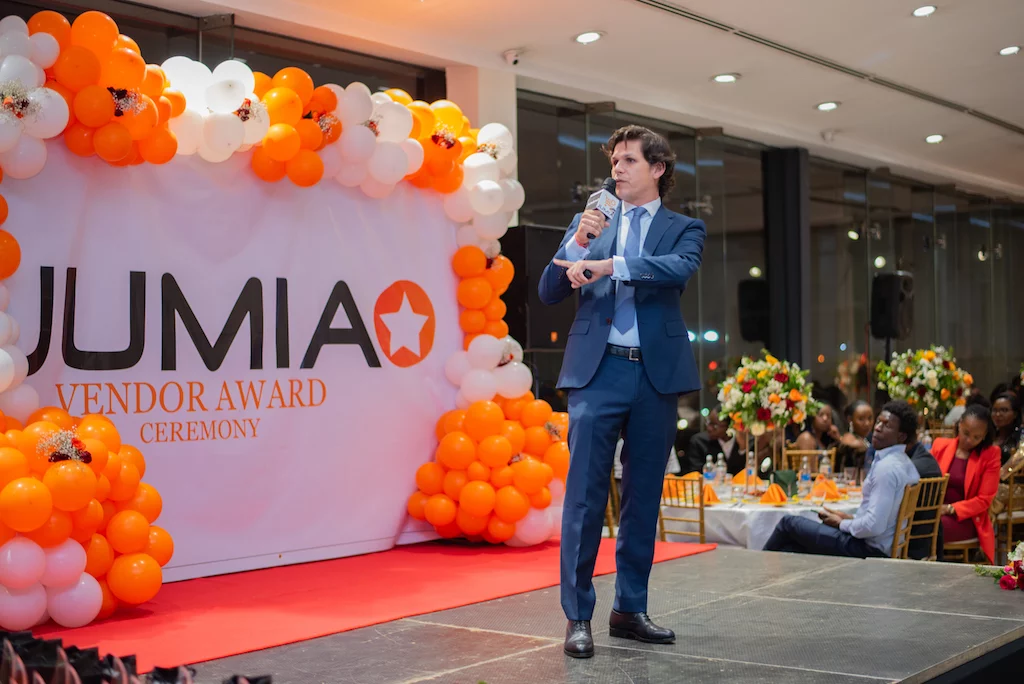
Juan Seco spent roughly a decade at Jumia, working across technology, commerce and financial services, including as the company’s chief financial officer. Image Source: Swalanyeti.co.ke

Seco realised Jumia’s problem was bigger than adding more payment integrations. It needed a layer in the middle to connect them. “This is broken. We need something in the middle,” was essentially the conclusion he reached.

That thinking helped lead to Jumia Pay, the e-commerce company’s fintech payments platform, and, later, a deeper focus on financial technology.

He saw similar problems on the banking side. Corporate financial services that should have been digital still involved cumbersome processes. A corporate card could effectively behave like a prepaid instrument. Transactions could require physical interaction with bank branches.

For someone who had spent years exposed to digital banking in North America, the contrast was striking. The opportunity was not to copy the banking systems he had known elsewhere but to build around the realities of African consumers.

At Jumia Pay, that thinking expanded into lending, including working-capital products for sellers, buy-now-pay-later integrations, consumer credit in Egypt, microloans in Nigeria, and other financial products designed around transactions already taking place on the platform.

From remittances to a “remittance-led neobank” 

That lesson followed him to Mukuru, where Seco joined in 2023 and found something many fintechs spend years trying to build: trust.

Mukuru had spent two decades moving money across borders, earning the trust of millions of customers who relied on it to send money home. But Seco saw that the person receiving the money was just as important as the person sending it.

Seco noticed that people in countries such as Zimbabwe, Malawi, and Botswana were not necessarily asking for a complicated new financial product. They wanted the thing they already understood to work better.

That became the foundation of his idea for a remittance-led neobank, with Mukuru using the trust it has built through moving money across borders as the starting point for a broader financial relationship with its customers.

“Remittance is the tip of the spear,” Seco said. “It is the first transaction and, in many cases, the first time we have that relationship with the customer. The opportunity is to take that trust and make the customer’s everyday financial life easier.”

According to Seco, remittance is the entry point that gives customers a reason to trust the platform and creates the opportunity for Mukuru to serve more of their everyday financial needs.

Instead of the money arriving and immediately disappearing into cash, it can remain in a wallet. The customer can pay a bill, make a purchase, receive a salary, send money elsewhere, or eventually access other financial services.

Seco is careful not to frame Mukuru’s expansion as simply selling more products to existing customers. Instead, he wants each new service to fit naturally into how customers already manage their money and solve a financial need they already have. “They should be an extension or adjacent to what the customer already does,” he said.

Making the money usable after it arrives 

That thinking is becoming increasingly visible in Mukuru’s products.

In Botswana, for example, Mukuru recently launched a physical Visa debit card linked to its wallet, allowing customers to spend from their wallet balance at retailers and withdraw cash from automated teller machines (ATMs). The idea is deceptively simple: money sent by a relative overseas can become immediately usable money rather than something that requires another step before it can be spent.

Seco sees this as the practical expression of Mukuru’s philosophy of meeting customers where they are. “At Mukuru, we always talk about meeting our customers where they are,” he stated.
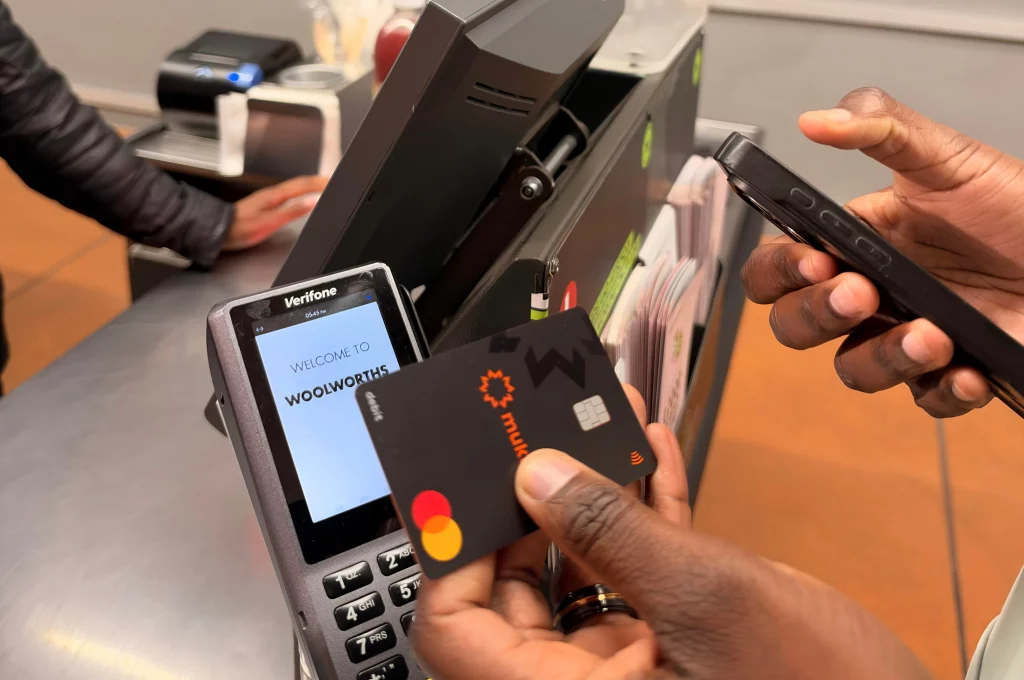
Juan Seco says the Mukuru card is designed to turn money received through remittances into money customers can use for everyday payments. Image Source: Mukuru

That means meeting customers wherever they are, whether through Mukuru’s agent network, USSD, WhatsApp or increasingly through digital accounts. This is where the Bank Zero partnership in South Africa becomes important.

Mukuru has partnered with Bank Zero to provide banking infrastructure behind its new account and card offering. Customers can receive salaries and other payments, make electronic payments and use their cards for everyday transactions, while Mukuru continues to own the customer relationship and experience.

It is a model that makes sense for Seco because Mukuru does not have to become a traditional bank in order to offer more banking functionality.

Bank Zero provides the underlying banking infrastructure, while Mukuru brings the customers, distribution, technology and financial-services experience.

The partnership is already significant in scale. About 500,000 Mukuru customers are being migrated onto Bank Zero’s infrastructure, contributing to a combined Bank Zero customer base of more than 700,000 end customers.

The 20-metre philosophy 

Seco believes the significance of those numbers lies less in their scale than in what they enable: customers can move from cash to digital financial services without having to start their financial journey all over again, an important shift in markets where cash and digital money still coexist.

“Just because someone transacts in cash should not mean they have access to fewer financial services,” Seco explained to TechCabal.

For Seco, success is not measured in app downloads or digital card issuances alone, but in making the transition between cash and digital value completely frictionless.

“Just because someone transacts in cash does not mean they should be excluded from formal financial services,” Seco emphasizes. Whether interacting via USSD, WhatsApp bots, agent networks, or debit cards, Mukuru’s mandate is to meet consumers within their existing habits.

Which brings the narrative back to a 76-year-old mother in Harare.

For fintech analysts, financial inclusion is often discussed in abstract metrics: regulatory licences, transaction throughput, and API integrations. For a mother collecting her monthly support, it boils down to something far more practical: the money arrives safely, predictably, and without unnecessary travel.

Her journey was 20 metres. In an industry often obsessed with technological novelty, Juan Seco’s vision for Mukuru proves that the most profound financial innovations shorten the distance between receiving money and using it.

True scale demands moving beyond surface-level integrations to robust execution. We’ve filtered the noise out of Moonshot 2026, optimising the conference strictly for high-calibre connections between startup founders, global financial operators, enterprise leaders and individuals rewiring Africa’s technical frameworks. Get 20% off Early Bird tickets for a limited time.
§

After decades in philanthropy, Derek Lubner discovered that giving money was simple; verifying where it went was the real challenge. In conversation with PHATHISANI MOYO,  the iZinga Assist co-founder explains how he plans to repair the trust deficit between donors and grassroots NGOs. 

When Derek Lubner was managing his late parents’ foundation, Make an Immediate Difference, he routinely asked beneficiary non-profit organisations to submit wish lists for the upcoming year. 

If an organisation wanted cricket bats and nets, a classroom or a soccer field, the co-founder and chairman of iZinga Assist, digital non-profit verification and support platform, would consider the request and agree to fund all or part of it. His only condition was that the organisation send him a photograph showing what the money had paid for.

Over the years, he estimates that barely a quarter of the organisations ever sent the requested pictures, leaving him with no straightforward way to confirm whether the equipment had been purchased or the project delivered. 

For someone dedicated to supporting grassroots community initiatives across South Africa, the omission was frustrating. Yet it also forced him to reconsider the administrative burden traditional donors impose on frontline social workers.

“I could have blamed the organisations and cut their funding,” Lubner told TechCabal. “Instead, I realised we needed to help them meet those compliance requirements.”

That conviction spurred the creation of iZinga Assist, co-founded with chief executive Henk Swanepoel. The digital platform was designed to make grassroots non-profits more visible, structurally sound, and easier for donors to vet.

In a sector where registration alone does not establish whether an organisation is active, well-governed or accountable for its funding, the platform digitally checks NGOs’ documentation and offers resources to help them address administrative gaps. The goal is twofold: give donors reliable data before deploying capital, and prevent administrative paperwork from locking legitimate community leaders out of funding pipelines.

Lubner had seen first-hand that an organisation can be passionately rooted in its community while remaining ill-equipped to meet the rigorous reporting standards demanded by institutional philanthropists.

Learning to look beyond the donation

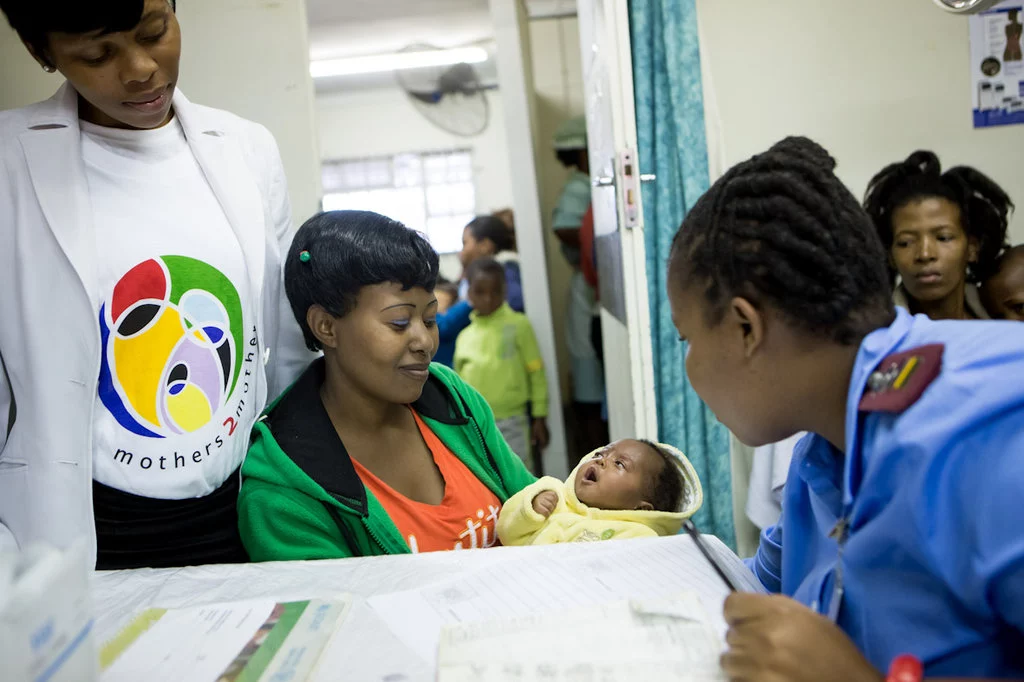
Lubner’s perspective had been shaped by nearly three decades in civil society, including a board seat at Mothers2Mothers since its inception in 2001. Founded in Cape Town during the height of the HIV/AIDS epidemic, the maternal health organisation pairs mothers living with HIV with pregnant women confronting new diagnoses, providing frontline guidance on treatment adherence and child protection.

The organisation demonstrated how social intervention succeeds when built around lived experience and backed by professionalised systems. Notably, Mothers2Mothers insisted on formally employing its mentor mothers rather than relying on unpaid volunteer labour, while resisting mission creep despite persistent donor pressure to chase unrelated grants.

Derek Lubner has served on the board of Mothers2Mothers since its founding in 2001, an experience that shaped his understanding of how non-profits can deliver meaningful community support. Image source: Global Living

Managing his family’s portfolio of 35 to 40 local non-profits provided the complementary funder’s perspective. 

It made clear that the chronic reporting failures he witnessed were rarely acts of fraud; they were symptoms of severe under-resourcing. Small social initiatives simply lacked the administrative bandwidth to produce institutional-grade documentation.

That realisation informed the development of iZinga Assist during the COVID-19 pandemic. Rather than penalising under-staffed teams, the platform was conceived as an operational scaffold to help them structure their governance and become investor-ready.

“We wanted to shine a light on the under-served tier of the sector,” Lubner explained. “The objective is to make these organisations both verified and visible to prospective funders.”

Making organisations easier to trust

To secure verification, iZinga Assist requires non-profits to upload roughly 20 statutory documents spanning founding constitutions, board charters, tax compliance, and audited financial statements. Where documentation is missing or inadequate, the platform supplies standardised contract templates, governance guidelines, and direct coaching.

Onboarding and verification remain completely free for applicant organisations, a deliberate choice to ensure limited cash reserves do not prevent legitimate groups from demonstrating compliance.

“NGO leaders often do not know what they do not know,” Lubner noted. “We try to lift that administrative burden, including by maintaining a secure cloud repository for their files so they are always audit-ready.”

According to Lubner, the platform has onboarded more than 500 organisations, with roughly 110 achieving full verification. Completing the audit often takes months or even years, as many grassroots teams either have incomplete records or feel apprehensive about disclosing internal books.

South Africa’s non-profit register provides a count of registered organisations, but registration alone does not establish whether an organisation remains active, maintains its records or delivers the work described in its founding documents. The scale of the sector makes that distinction important.

iZinga Assist cited 289,852 organisations on the Department of Social Development’s register at the end of September 2025 and Trialogue’s estimate of R13.1 billion ($797.8 million) in corporate social investment spending in 2025. Those figures describe the wider sector, not funds verified or tracked by iZinga Assist.

For Lubner, the opportunity is to close the information gap between organisations seeking support and donors who need confidence in how their money will be used. That includes South Africans living abroad who want to support causes at home but may struggle to identify credible organisations.

He envisages donors being able to identify causes they care about and receive updates in line with their preferences. Someone interested in sport, for example, could support a community cricket programme and receive confirmation that equipment purchased with their donation reached the intended organisation.

The platform is exploring ways to make that process easier to track, including payment arrangements that could confirm when money has been spent on an agreed item. In one model Lubner describes, an NGO could use a payment card to purchase something specific, such as cricket bats, with the donor receiving confirmation of the transaction.

The objective is to replace philanthropic guesswork with verifiable paper trails. Yet Lubner readily concedes that proof of transaction is not synonymous with lasting community transformation.

“‘Impact’ is a term thrown around casually, but its definition varies wildly,” he explained. A community initiative might miss an arbitrary numerical target due to unforeseen local unrest or weather events without rendering its underlying mission invalid.

That distinction is vital: a photograph of soccer balls confirms procurement; it cannot determine whether youth delinquency declined or whether sports participation improved mental health. A credible verification mechanism must clearly delineate administrative compliance from long-term social efficacy.

Building trust without creating another barrier

iZinga Assist faces its own verification challenge: no external regulator currently audits its proprietary methodology, and remote document checks do not substitute for on-the-ground inspection.

“Donors have to place confidence in our vetting, and we recognise that scrutinising our own credibility is a fair demand,” Lubner acknowledged.

Digital document reviews confirm statutory registration and corporate governance, but they cannot prove that an organisation is actively running the clinics or food kitchens it claims. The platform’s forthcoming five-star rating index will have to clearly disclose where documentary verification ends and physical validation begins.

To solve this, Lubner is courting commercial banks and corporate donors to mobilise their workforce for volunteer field visits. Properly trained corporate volunteers could perform periodic on-site spot-checks, providing donor validation while connecting corporate personnel directly with local communities.

Lubner insists accountability must be mutual. Donors must communicate their metrics with clarity rather than imposing shifting reporting targets. “Too often, non-profits spray hundreds of proposals into the dark, while donors sit on capital because they cannot separate genuine operators from paper organisations,” he said. “We need symmetry in that relationship.”

Derek Lubner and Henk Swanepoel co-founded iZinga Assist to help non-profit organisations demonstrate their credibility, improve governance and connect with donors. Image source: iZinga Assist 

Achieving platform sustainability is the next operational test. As core verification will remain free for non-profits, iZinga Assist must monetise by licensing its vetting infrastructure to corporate CSI teams, philanthropic foundations, and wealth managers who require compliance-as-a-service.

“I am not looking to make a fortune from iZinga Assist; the goal is operational self-sufficiency,” Lubner said. His five-year objective is to assemble an active network of several thousand verified non-profits that use the portal to source legal templates, professional development courses, vetted consultants, and verified funding leads.

What began decades ago as a quest for missing photographs has expanded into an ambitious structural intervention. Lubner is attempting to rewire an opaque philanthropic sector where well-intentioned donors and committed grassroots organisations remain divided by paperwork and mutual distrust.

Whether iZinga Assist succeeds will depend not just on the code it deploys or the documents it checks, but on whether it can command the same institutional credibility it is asking South Africa’s non-profits to prove.

True scale demands moving beyond surface-level integrations to robust execution. We’ve filtered the noise out of Moonshot 2026, optimising the conference strictly for high-calibre connections between startup founders, global financial operators, enterprise leaders and individuals rewiring Africa’s technical frameworks. Get 20% off Early Bird tickets for a limited time.
Moonshot mast head

§

Vuyani Jarana, CEO of Ilitha Telecoms, is taking affordable broadband into underserved townships and rural communities. In a conversation with PHATHISANI MOYO, he explains why connecting homes is only the beginning, and how education, healthcare and local businesses could turn internet access into lasting economic opportunity.

As a boy growing up in Eastern Cape Province, Vuyani Jarana was fascinated by the voices coming out of a radio. He and his friends wondered how people could speak from inside a box, so they would open discarded sets and try to fix them.

“We wanted to understand how it worked, even though there were no people inside it,” recalls the chief executive officer (CEO) of Ilitha Telecommunications, a township and rural broadband provider founded in 2019.

Television was another attraction. One household in his village had a television and a generator, turning its lounge into an informal cinema where children gathered after football to watch movies. The room often became chaotic as they took over the entire space, Jarana told TechCabal in an interview on Monday.

Today, the former Vodacom executive, a mobile network connecting millions across Africa, is building broadband networks for communities like the one where he grew up. Ilitha wants to connect 600,000 homes, backed by R500 million ($30.4 million) in funding from Absa Corporate and Investment Banking (CIB). In 2025, the company also secured a R420 million ($25.5 million) investment from Meridiam, a European sustainable infrastructure investor, to expand high-speed fibre access to at least 500,000 low-income homes.

The goal is not simply to provide internet access, but to make broadband useful enough for people to invest in it, improve their lives and build businesses around it. That means understanding how people live, not just laying fibre and installing routers, according to Jarana.

A career he did not plan

Telecommunications was not Jarana’s first choice. He had been accepted to study medicine and chemical engineering, but his plans changed when his father died while he was writing his final high school examinations. As the youngest child in a household without a breadwinner, he felt responsible for helping support his family.

“I decided not to go straight to university,” he said. “Instead, I looked for a job that would train me while paying me.”

He began his career as a trainee technician at Transkei Post and Telecommunications, a former telecoms operator, in an arrangement that combined formal training with practical work. The organisation paid for his studies, allowing him to earn an income while continuing his education part-time. He later joined Vodacom and moved into strategic and leadership roles before taking up a position at South African Airways (SAA), the national flag carrier airline.

His engineering background taught him to break problems into manageable parts. Corporate life taught him that a company’s assessment of its performance can differ sharply from the customer’s experience.

“When you work on the operations side, it is easy to look at your own standards and assume that you are doing well,” he said. “But when you manage customer experience, you begin to see the gaps.”

A company can invest in infrastructure and design service standards. However, customers judge it by whether the connection works when needed, whether the price is affordable, and whether the service is reliable. That distinction would shape Ilitha’s approach to underserved communities, where simply offering a cheaper version of a product designed for wealthier households may not be enough.

Building for the way people live

After leaving SAA, Jarana returned to a business opportunity he had considered before joining the airline. He brought colleagues together to address a gap in the telecommunications industry. Demand for broadband was growing, but many township and rural households lacked access to reliable, high-capacity connections.

The Covid-19 pandemic exposed the problem. As work, education and everyday services moved online, some households struggled with connections too slow or unreliable to support even a Microsoft Teams call.

Pricing presented another barrier. Traditional mobile data models often reward customers who sign long-term contracts or buy large bundles upfront. Those with less money to spend can end up paying more per gigabyte while having fewer options for reliable broadband.

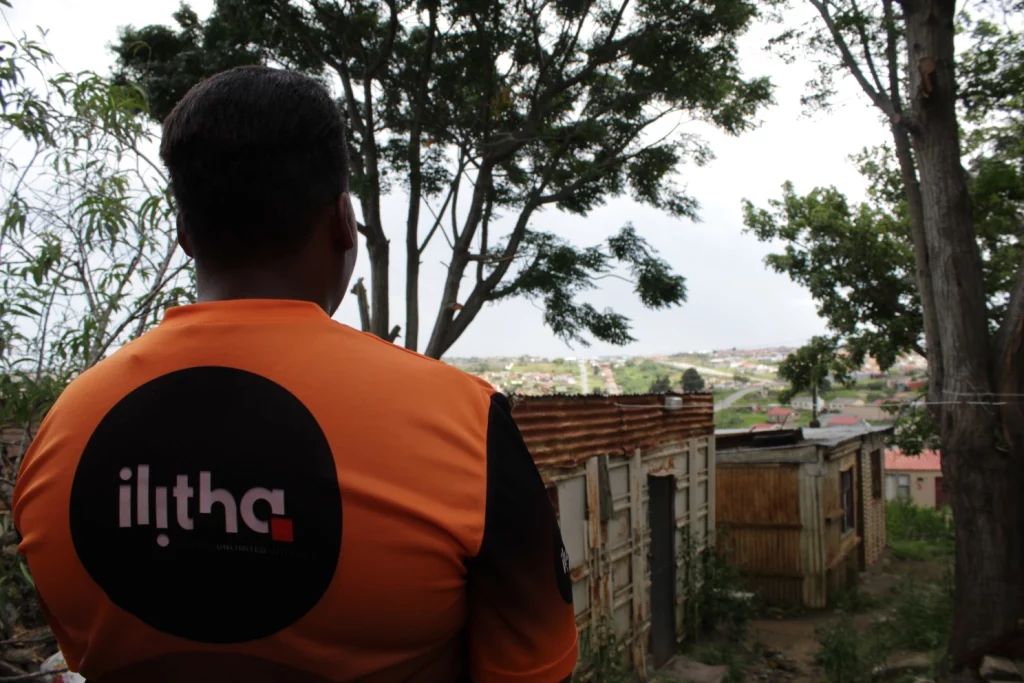
Ilitha Telecoms has expanded into 27 township and peri-urban communities across the Eastern Cape Province and KwaZulu-Natal Province in about 18 months, with Absa funding set to support its next phase of growth. Image Source: Ilitha Telecoms 

Ilitha was built around a different proposition: affordable, dependable connectivity designed for how people use their homes and neighbourhoods.

The company expanded into 27 township and peri-urban communities across the Eastern Cape and KwaZulu-Natal provinces over 18 months. The Absa funding will support its next growth phase, but Jarana says expansion must be financially sustainable.

“We have an ambition to connect 600,000 homes within a defined period, but we must do it through financially practical phases that bring more households online within the right commercial structure,” he said.

Each community has different population densities, connection costs and infrastructure requirements.  He cautioned that expanding too quickly without a viable business model could leave the company with an expensive network it cannot maintain.

“There is growing interest in the township market, and some entrants may approach it as a land grab,” Jarana said. “As a smaller player, we are comfortable choosing the areas where we believe we can build a strong proposition.”

For Ilitha, success depends on whether customers can use the service consistently and whether the economics work for both the household and the business.

The neighbourhood is part of the network

One response is Ilitha’s nomadic broadband model, which keeps customers with an active pass connected across participating homes rather than tying access to one address.

“A nomadic service builds on that neighbourhood effect and also allows us to address some of the needs usually associated with mobile broadband,” Jarana explained.

The model reflects how people move between neighbours’ homes and spend time within their communities. Instead of treating broadband as a service confined to one household, Ilitha allows its network to serve customers across participating homes.

The prepaid model presents a separate challenge. A household may not be able to recharge every week, even though its router remains part of the installed infrastructure. Ilitha asks customers to keep their routers switched on so others can benefit from the network. This helps the company recover infrastructure costs while extending the network’s usefulness.

But affordability alone does not guarantee regular use. Customers also need reasons to keep paying for the service.

“If someone only uses the internet for WhatsApp and a few other basic activities, many products can meet that need,” Jarana said. “But when a household uses broadband for streaming films and television, educational content for children, or security cameras, the value of a high-capacity connection becomes much clearer.”

These activities encourage customers to recharge regularly. They also demonstrate why Ilitha wants to build services around connectivity rather than simply sell internet access.

“We have come to see use cases as part of the social contract between us and our customers,” he said.

What happens after the router is installed?

Jarana wants Ilitha to support services that create jobs and widen access to opportunities often easier to find in wealthier communities.

Education is a priority. Children in township and rural households have similar ambitions to their peers elsewhere, but many lack access to additional learning support. Online tutoring can be expensive even as unemployed teachers and graduates look for work.

Ilitha is exploring partnerships to provide curriculum-aligned content for learners from Grade 1 to Grade 12, alongside platforms that could help teachers operate as independent service providers.

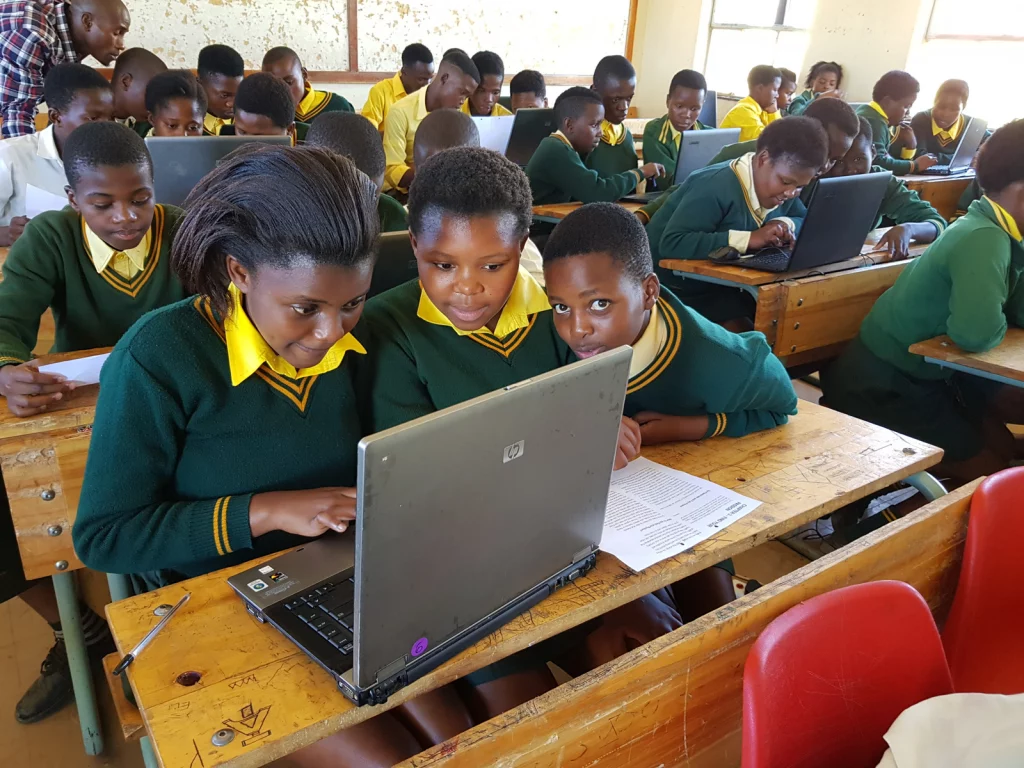
Ilitha Telecoms is exploring education partnerships to give learners in township and rural communities access to curriculum-aligned digital learning resources and additional academic support, while creating opportunities for teachers to offer tutoring services.  Image source: UR Global

“Children in these communities have the same aspirations as children anywhere else,” Jarana said. “They want to become doctors, engineers, scientists, presidents and company leaders. They should not have to rely on chance to get the coaching and support they need.”

Healthcare is another potential application. Ilitha says it is working with TruMD, a South African virtual healthcare provider, to provide on-demand doctor consultations. The broader idea is to make broadband a gateway to useful services while creating opportunities for local businesses and skilled workers.

Building the network has itself required close coordination between local businesses and larger contractors. Jarana said Ilitha initially considered outsourcing more construction work but learned that connecting homes at scale requires continued involvement in the communities where it operates.

“You cannot outsource the work and walk away,” he told TechCabal.

The next challenge is maintaining the network efficiently. Ilitha is developing digital-twin capabilities to monitor routers, assess network performance and identify why devices go offline. Such tools could help reduce maintenance costs as the business grows.

Jarana insists that social impact must go hand in hand with commercial discipline.

“It is not charity,” he said. “If pricing and delivery are designed properly, people are willing and able to pay for a service that is accessible and useful, while the business can still make a margin.”

Connectivity cannot stop at the town boundary

Jarana believes rural connectivity requires greater infrastructure investment that lets smaller internet service providers and local entrepreneurs reach communities that are expensive to serve.

Satellite services could help where fibre is unavailable, provided prices are affordable. Ilitha sees them as potential enablers rather than necessarily direct competitors.

He called on government and development finance institutions to help drive digital transformation by using schools, clinics, hospitals and police stations as anchor customers for fibre networks. Jarana maintains that their demand could help justify the initial investment, while the same infrastructure serves surrounding households and businesses.

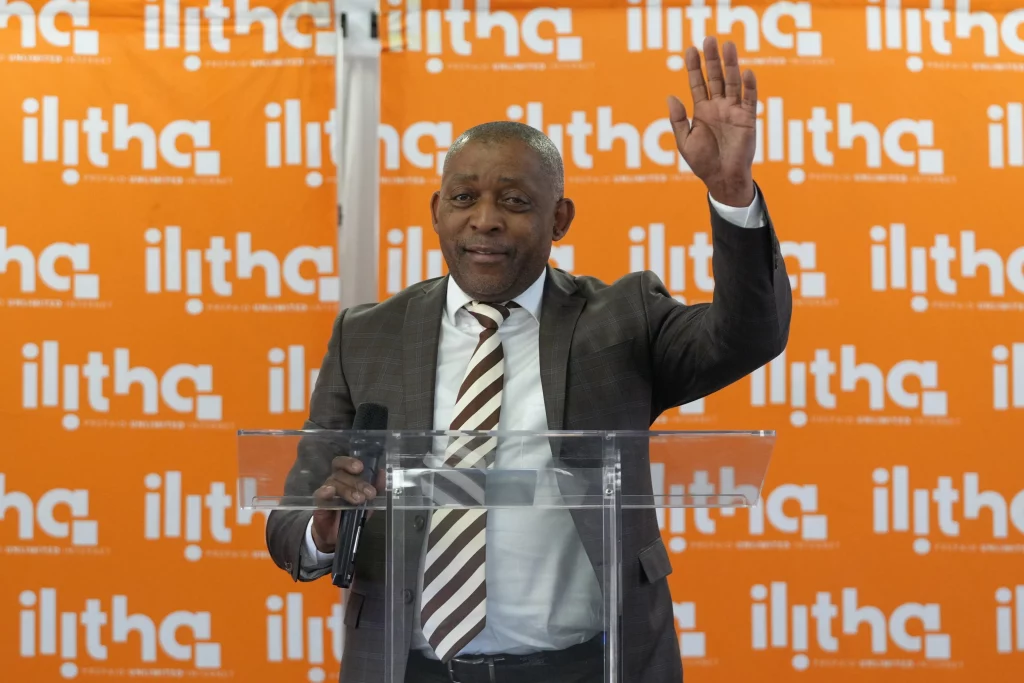
Vuyani Jarana says affordable broadband can open up access to healthcare and economic opportunities in underserved communities, turning internet connectivity into a platform for local development. Image Source: Ilitha Telecoms

“A young person or locally owned business should be able to use that infrastructure to connect 200 or 500 homes and build a viable local business,” Jarana said.

The missing pieces in many areas are the underlying infrastructure and financing models that make such businesses possible.

Jarana applies the same thinking to education. South Africa’s universities cannot accommodate every high school graduate, and building more campuses will not be enough. Online learning could widen access, but only if students have reliable connectivity and quality teaching rather than a digital reproduction of the emergency arrangements used during the pandemic.

“If we do not act now, we will face the same questions in 10 or 15 years about what opportunities are available to the children coming through the system,” he said. “We need to start building those opportunities today.”

True scale demands moving beyond surface-level integrations to robust execution. We’ve filtered the noise out of Moonshot 2026, optimising the conference strictly for high-calibre connections between startup founders, global financial operators, enterprise leaders and individuals rewiring Africa’s technical frameworks. Get 20% off Early Bird tickets for a limited time.
Moonshot mast head
Web hosting by Somee.com