×
Tech

Kenya’s fintech reforms promise clarity but could delay investment

Kenya’s fintech reforms could delay ecosystem investment

Kenya is proposing approval requirements for significant investments in payment companies, potentially lengthening fundraising for startups as the central bank strengthens its oversight of the industry.

The draft National Payment System Bill, 2026 would require investors acquiring at least 10% of a licensed payment service provider or payment system operator to obtain written approval from the Central Bank of Kenya (CBK). Incoming significant shareholders would also undergo regulatory vetting, a standard process at other financial institutions, such as banks.

The proposals would make approval a condition of completing investments. Fintech founders could face a longer time between securing an investor’s commitment and completing the transaction. A company running short of cash would have to account for a decision that neither its board nor its prospective backers could control.

“A significant change of ownership of a licensed payment service provider or a licensed payment system operator shall be subject to the prior written approval of the Central Bank,” clause 58 of the Bill states.

Repeal of old laws

The requirements are part of a proposed repeal of Kenya’s fintech law, which would establish separate licensing categories for businesses including electronic wallets, payment gateways, and money remittance providers. The overhaul introduces measures that the regulator says will encourage competition in a sector dominated by banks and telcos, and also bring tighter controls over capital, ownership and management.

Agnes Aistleitner, managing partner of First Circle Capital, tells me that the proposal adds complexity and costs to investing in Kenya, which is already very expensive and, so far, hasn’t been the most lucrative fintech market, apart from Safaricom and a few others. “Ultimately, I think it raises the bar for investment opportunities in Kenya,” she says.

While the draft sets a threshold for ownership approval, it does not specify how quickly CBK must decide on a transaction. 

The uncertainty would concern the closing date. An investor could agree to fund a business but make the funding contingent on regulatory approval, leaving the company unable to count on the money until approval is granted. A provider with limited cash would need to begin raising earlier or arrange financing to cover the wait.
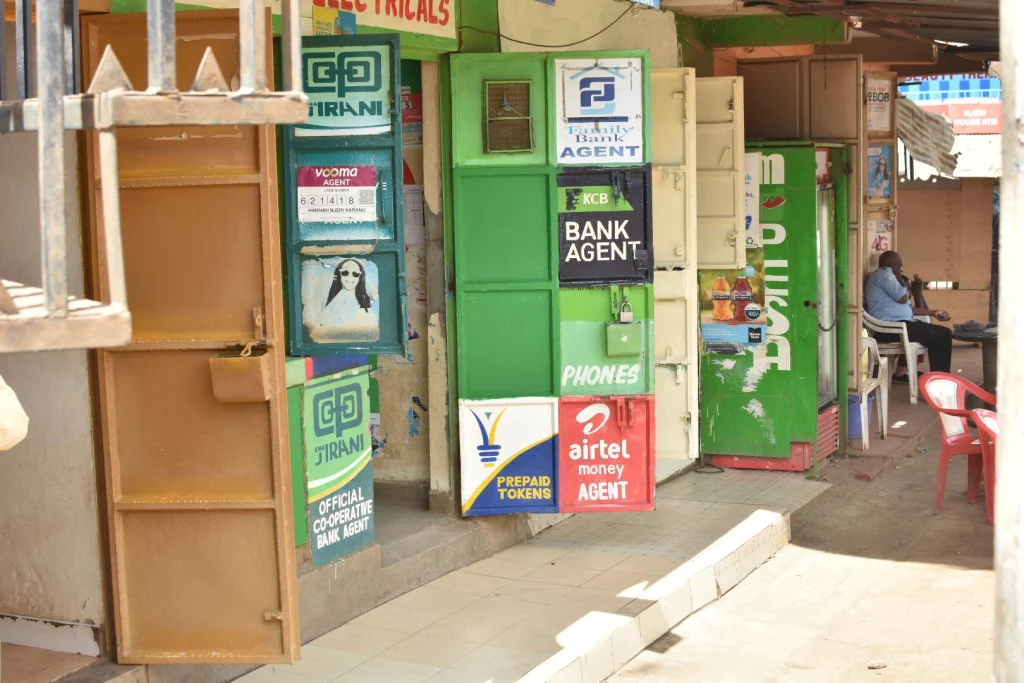
A mobile money agent in Nairobi. Image source: NMG

The timing could become particularly important for providers raising money to meet the bill’s capital requirements. The draft proposes a minimum capital requirement of KES 250 million ($1.9 million) for electronic money issuers and KES 50 million ($385,178) for wallet providers, with existing payment businesses given 1 year from the law’s commencement to comply. A company bringing in a significant shareholder to meet those requirements would need to complete both the investment and the ownership approval within its compliance timetable.

A temporary cash injection would not necessarily resolve the problem. Clause 10 excludes “shareholder loans or advances” and “unpaid, partly paid, or contingent capital commitments” from paid-up capital. A founder could therefore secure sufficient funds to keep the business operating without meeting the regulatory minimum.

Investor scrutiny is already part of Kenya’s fintech industry. The 2014 regulations require CBK to assess and approve significant shareholders, directors and senior managers. They set the threshold at 5% for unlisted providers and 10% for listed companies.

Therefore, the bill’s proposed 10% threshold would be higher for unlisted providers. The effect of the proposed changes would depend on how the approval process works alongside shareholder vetting, and whether it becomes predictable.

“The new significant shareholders shall undergo the same vetting as the existing shareholders,” clause 58 says.

Such assessments could cover matters including integrity, competence, business conduct, and bankruptcy, with investors subject to an examination of their suitability.

The requirements could also reach investments below the headline threshold. Clause 11 of the proposed law allows the CBK to vet smaller shareholders when it suspects that a holding has been reduced to avoid certification, or when an investor exercises control through associates.

“It’s not very attractive for investors. If we have to look at bridge financing or restructuring down the line, that would make it even more complicated. That would also factor into whether we would want to do a deal in the first place,” Aistleitner said.

Exit plans would face scrutiny too. The draft says “no merger or acquisition of a payment service provider or payment system operator shall be done without the prior written approval of the Central Bank”.

For a company unable to raise capital independently, a sale to a larger rival could thus require regulatory clearance as well. The same would apply to investors seeking an acquisition as their exit from the business, subject to any applicable competition review.

These requirements could favour investors able to commit time and resources to regulatory due diligence. They could also encourage companies to begin fundraising earlier, negotiate more time between signing, and completion, and prepare ownership and governance information before approaching CBK.

Bringing certainty

There is a benefit in some of these changes. Currently, Kenya’s fintech sector is regulated by the Central Bank of Kenya Act, the National Payment Systems Act, the National Payment Systems Regulations of 2014, and the e-money Regulations of 2013, all of which apply to fintechs.

This has put remittance and payment startups on a collision course with Kenyan authorities, with law enforcement agencies, including the Financial Reporting Centre (FRC) and the Asset Recovery Authority (ARA), freezing accounts and seizing assets of sector players on money-laundering charges.    

In 2022, CBK ordered local financial institutions, including banks and mobile money service providers, to cut ties with fintechs, citing unspecified threats to the country’s financial systems. The regulator said at the time that the firms were operating without authorisation.

Clear licences and a consistent approval process could make payment businesses easier to assess and reduce uncertainty about their right to operate. The Treasury and CBK say the overhaul is intended to promote competition and innovation while protecting consumers and financial stability.

A well-run process could allow investor vetting to proceed alongside commercial negotiations. A slow or unpredictable one could leave a company with an agreed deal but insufficient certainty to plan hiring, expansion, or even its next few months of operations.

True scale demands moving beyond surface-level integrations to robust execution. We’ve filtered the noise out of Moonshot 2026, optimising the conference strictly for high-calibre connections between startup founders, global financial operators, enterprise leaders, and individuals rewiring Africa’s technical frameworks. Get 20% off Early Bird tickets for a limited time.

§

South Africa’s Companies and Intellectual Property Commission wants an AI chatbot capable of handling an estimated two million customer interactions per month. Its tender covers development, integration, hosting, security, and support over a three-year period. But one condition exposes the challenge for a startup pursuing the contract: no advance payments. Invoices become payable within 30 days only after receipt and acceptance of work.

For a startup, winning the contract is only the beginning. It must fund the people, technology, and infrastructure needed to deliver before it can collect payment. That means a deal that promises revenue and credibility can also tie up scarce cash, leaving a young company to shoulder the cost of serving a public institution before seeing a return.

This tension runs through AI Made in Africa, a report by GIZ and Briter set to launch in October 2026. Among surveyed businesses, 44% target governments, while 32% identify access to public procurement as a policy priority. Yet founders face long sales cycles, expensive infrastructure, and a need for patient capital — resources that can be difficult for early-stage companies to secure.

The result is a gap between government demand for AI and local startups’ ability to meet it. Public contracts could offer young companies a route to revenue and scale, but interest alone does not create a viable market. The test is whether procurement systems allow startups not only to qualify for contracts and deliver the technology, but also to survive the wait between investment and payment.

A pilot is not a purchase

AI
On September 21, 2025, Nigeria’s Minister of Communication, Innovation, and Digital Economy, Bosun Tijani, announced the launch of N-Atlas, an AI model that speaks different local languages. Image credit: FMCIDE.

Government spending on AI takes different forms. It can fund experiments, pay for software, or support large infrastructure projects. These are not the same thing, and counting them all as business opportunities can make the market look bigger than it is for startups.

Nigeria’s N-ATLAS project shows why the distinction matters. The government announced the language-model project in April 2024 and unveiled it in September 2025, working with Lagos-based Awarri. This confirms that the government and the company worked together to develop the technology. But it does not establish how long procurement took, how much the contract was worth, or when payments were due. TechCabal’s reporting also found that the project continued to rely on foreign cloud infrastructure.

Launching an AI product can indicate technical progress, but it does not tell us whether the developer is earning steady revenue from the government. In the same way, funding from grants or support through a consortium does not automatically mean a government agency has paid a company for its services.

The AI Made in Africa report captures founders’ frustration with the gap between product testing and building a lasting business. One respondent said that moving from short-term pilots to long-term partnerships with institutions would significantly accelerate growth. Startups want a chance to prove their technology on a small scale, but they also need a clear path to paid contracts once the trial ends.

While pilots allow governments to evaluate AI capabilities without long-term commitments, formal procurement tenders reveal the structural timelines and financial demands required when public institutions commit to full contract awards.

A procurement by the Southern African Development Community (SADC) illustrates how long that process can take. On October 8, 2025, the SADC Secretariat published a notice for a data-mining tool. It awarded a $160,550 contract on August 28, 2026, to South Africa’s Ai-T Consulting Services and Sambe Consulting, a cloud, business intelligence and data analytics consultancy established in 2006.

Almost 11 months passed between the notice and the award. This does not show how long it took to turn a pilot into a contract, or whether the suppliers have been paid. It does, however, show the time that can pass between a procurement notice and the selection of a supplier.

For startups, that delay is more than an administrative detail. They still have to pay engineers, cover operating costs and keep their businesses running while a potential contract moves through the system. An expression of interest cannot pay salaries.

Eligibility and structural barriers shape the market

Procurement rules serve an important purpose. Governments need secure systems, reliable suppliers, and proof that contractors can deliver. But these requirements can also favour companies with strong finances and experience navigating complex tenders, even when smaller firms have the technical skills to do the job.

The CIPC chatbot tender requires tax documents, supplier registration, security checks and compliance with data protection rules. Bidders must also attend a compulsory briefing and submit documents in hard copy and on a USB drive. The project goes beyond building a chatbot: it requires integration with internal systems, payment gateways and several communication channels.

For startups, that means technical ability alone may not be enough. They must also prove they can meet the administrative requirements, manage the project and support a complex public service.

Kenya’s second-phase Nairobi Intelligent Transport System tender shows how funding rules can further narrow the field. Business Daily Africa reported that the approximately $83.8 million project is financed through South Korea’s Economic Development Cooperation Fund, with eligibility restricted to South Korean firms.

The project covers smart traffic lights, automated enforcement and vehicle detection systems. The tender represents a procurement opportunity, not proof that the full amount has been paid out.

Local companies cannot win such a contract simply by offering better software. They may have to participate through partnerships or subcontracting instead.

Still, these examples do not prove that foreign companies dominate all public AI contracts. SADC awarded its data-mining contract to South African firms. Nor is there sufficient evidence to conclude that local startups are largely limited to unpaid pilots, while multinational companies receive most of the public AI spending. Establishing that would require systematic data on contract awards and actual expenditure.

The key question is whether governments are building local technical capacity or simply involving local companies in projects led by others. Answering it requires public records that show who wins contracts, what they deliver, and where the money goes.

Getting paid takes time

Winning a contract is only half the challenge. Startups must also finance the work before payment arrives.

Under CIPC’s terms, the 30-day payment period begins only after the work has been received and accepted. With no advance payments, suppliers must cover their costs upfront. They must also account for hosting, software licences, and usage costs throughout the contract.

These expenses can be significant for AI companies. The GIZ–Briter report found that 65% of surveyed businesses identified cloud and computing resources as their largest AI-development expense category. This means 65% selected cloud and compute as their biggest cost category; it does not mean these expenses account for 65% of every company’s budget.

Late payment adds another risk. The available evidence does not establish that African governments routinely take 90 to 240 days to pay suppliers. But South Africa’s National Treasury reported that national departments paid 102,439 invoices worth R6.6 billion ($398.2 million) after 30 days in 2025/26. These figures cover suppliers across sectors, not AI companies specifically, but illustrate a payment risk that can put pressure on startups with high monthly cloud bills and engineering payrolls.

While waiting for government receipts, those businesses must finance continuing expenses from reserves, other revenue or borrowing, potentially shortening their cash runway and limiting further development. The report does not quantify startup-specific losses, but Treasury warns that late payments can undermine small businesses’ financial sustainability and ability to remain operational.

Governments could make procurement more accessible by linking paid pilots to clear purchasing decisions, setting precise acceptance criteria and publishing contract awards separately from actual spending. Eligibility rules could also protect public funds without treating a company’s short operating history as proof of a lack of technical ability.

For startups, the central issue is cash flow. Government contracts can offer scale, credibility, and steady demand, but only if companies have sufficient working capital to continue operating until they are paid.

True scale demands moving beyond surface-level integrations to robust execution. We’ve filtered the noise out of Moonshot 2026, optimising the conference strictly for high-calibre connections between startup founders, global financial operators, enterprise leaders and individuals rewiring Africa’s technical frameworks. Get 20% off Early Bird tickets for a limited time.

Moonshot mast head

§

Terra Industries, the Nigerian defence technology startup, has become one of the most recognisable names in the African deep tech sector.

Terra has earned the visibility. Founded in 2024 by Nathan Nwachuku and Maxwell Maduka, the company designs and manufactures autonomous drones, sentry towers and crewless ground vehicles, all connected through its proprietary ArtemisOS platform. In August, it closed a $52 million seed round, the largest in Africa. Terra offers a glimpse of what is possible if an ecosystem can support more companies to that stage. 

The United Nations Development Programme defines deep tech as technology built on scientific discoveries, engineering innovations and advances in research, with intensive research and development at its core. It includes companies developing drones and robotics, semiconductor and computing technologies, biotechnology, medical devices and some forms of artificial intelligence. 

Businesses in Africa’s tech ecosystem are mostly built around using technology rather than developing it. A fintech company can build a payments product without manufacturing the smartphone its customers use, just as a logistics startup can build software on top of cloud infrastructure or networks developed and operated by other companies. The underlying hardware and foundational systems already exist; these startups simply apply them to market problems.

Deep tech brings that technology into the company. To turn engineering breakthroughs into commercially viable products, such companies may need to design and repeatedly test prototypes, source specialised components, work with researchers and engineers, and access laboratories or manufacturing facilities. 

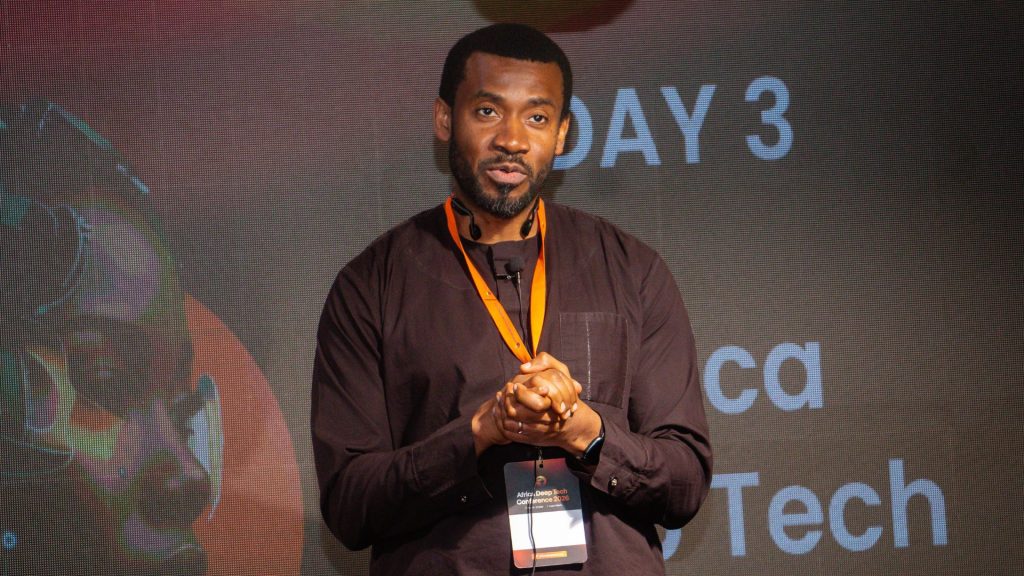
Chukwuemeka Afigbo is betting on Africa's Deep Tech
Chukwuemeka Afigbo, convener of Africa Deep Tech Foundation. Image source: Africa Deep Tech Foundation

Building deep tech is an uphill climb

For Chukwuemeka Afigbo, who convenes the Africa Deep Tech Foundation, a community focused on supporting deep tech builders and developing the ecosystem around them, hardware companies in the community have raised concerns about the cost of bringing components into the country. 

“The hardware folks would tell you there’s a lot of support they need that they haven’t necessarily seen. For example, like policies around the amount of money they pay to bring in components to build stuff in the country,” he said in a conversation with TechCabal in October. 

A 2021 baseline study commissioned by the Nigerian Communications Commission found that 84% of the hardware components used in Nigeria’s telecommunications sector are imported. Those components include printed circuit boards, semiconductors, connectors, antennas, and other electronic parts. For hardware companies building and testing products locally, components that cannot be sourced locally must be imported, exposing them to shipping costs, foreign exchange movements, customs procedures, and import duties.

Africa’s capacity to produce some of the technologies underpinning the global economy remains limited. The continent accounts for less than 1% of global semiconductor economic output, according to the African Academy of Sciences. Its position in the semiconductor industry is concentrated on design or testing.

The same constraints are becoming visible in artificial intelligence. AI is now one of the biggest technology conversations in Africa, but many of the products available are built on infrastructure developed elsewhere. Building the underlying systems requires specialised chips, data centres, engineering talent and research capacity, and Africa currently accounts for 0.6% of global data-centre capacity. 

Funding is also a constraint. In 2025, African startups raised $3.42 billion, with fintech accounting for $1.37 billion, or about 40% of the total, according to TechCabal Insights’ State of Tech in Africa report. A Briter Intelligence mapping of the sector found that African deep tech startups raised about $3 billion across 360 deals between 2013 and the first half of 2023.

The economics of building deep tech could help explain this disparity. Import costs and a thin research base can make a hardware company’s path to revenue longer and its failures more expensive than those of a software company. Capital tends to follow businesses where there is a clear route to generating returns on investments. 

Governments across Africa are paying attention to advanced technology, but AI has received a disproportionate share of that attention. Nigeria’s National Artificial Intelligence Strategy was published in September 2025; Kenya adopted a national AI strategy in 2025; Egypt updated its AI strategy; and South Africa has been developing an AI policy framework to guide the country’s approach to AI governance, development, and adoption.

The attention is understandable. AI is growing and attracting capital, but an AI-heavy policy agenda risks overshadowing the distinct, physical demands of the broader deep tech sector. As Afigbo notes, government awareness remains in its early stages. At the same time, interest and scattered initiatives exist; public policy has yet to match the capital intensity and supply-chain requirements of building hard tech on the continent. 

“Yes, there is government awareness and interest, but still relatively nascent,” he said. “A lot of good things are happening, but we need10 times more than that to happen. It’s a journey.”

Building the conditions for deep tech

The Africa Deep Tech Foundation has grown from a small online community into a network of more than 5,000 people, with a core group of about 200 deep tech practitioners across Africa and the diaspora, according to Afigbo. He said it has organised incubation programmes and rallied support for early-stage founders. Other companies are also working on pieces of the ecosystem. 

ChipMango, a semiconductor design and engineering talent development company, is training students and technical professionals in modern chip design across Africa. Signvrse uses AI-powered 3D avatars to translate speech into sign language in real time. NovFeed converts organic waste into high-protein fish feed to tackle food insecurity. Envisionit Deep AI automates radiology diagnostics in rural clinics. BasiGo and Spiro now manage large fleets of electric buses and motorcycles supported by battery-swapping networks.

For the ecosystem to support more companies on that journey, it needs to create conditions that make building deep tech easier. This could include capital, better access to manufacturing and specialised infrastructure, a deeper pool of engineering and research talent, and treating deep tech as a broader field than AI by developing policies and infrastructure that support the technologies underpinning the sector.

Terra’s success makes the possibility of a thriving deep tech sector easier to see. It shows that global investors are willing to back an African company building sophisticated physical technology. Ultimately, whether Terra remains an extraordinary outlier or becomes the vanguard of a broader movement depends on whether Africa’s tech ecosystem can evolve fast enough to meet the heavy demands of deep tech. 

True scale demands moving beyond surface-level integrations to robust execution. We’ve filtered the noise out of Moonshot 2026, optimising the conference strictly for high-calibre connections between startup founders, global financial operators, enterprise leaders and individuals rewiring Africa’s technical frameworks. Get 20% off Early Bird tickets for a limited time.
Moonshot mast head
Web hosting by Somee.com