×
Tech

A data centre is not a cloud platform: Why the distinction matters

Data centre vs Cloud platform: Is there a difference?

You have probably seen the words “data centre” and “cloud” used interchangeably. They don’t mean the same thing, and the difference matters. It shapes how businesses buy technology, how regulators write rules and where investors see opportunity.

A data centre is a building. It is a secure, purpose-built facility with reliable power, cooling, security and internet connections, so that computers can run around the clock. A cloud platform is a service. It is software that lets customers rent computing power, storage, and networking on demand, switch them on or off themselves, and pay only for what they use.

Think of an airport and an airline. The airport provides the runway, fuel, and terminal; the airline provides the service you actually book. Every cloud platform runs inside a data centre, but most data centres do not offer a cloud platform. Owning an airport does not make you an airline.

Data centre grading and cloud computing standards

Companies that rent space for their own servers in someone else’s facility are buying what the industry calls “colocation”. A facility’s reliability is rated on a four-level scale from the Uptime Institute. 

Tier I has no backup equipment, so any fault results in downtime. Tier II adds spares but has a single path for power and cooling. 

Tier III has more than one path, so any part can be serviced without switching anything off; it is the level most serious operators aim for. Tier IV survives any single failure. 

Be careful, though: “built to Tier III standards” is not the same as certified, so ask which certificate a provider actually holds.

The US National Institute of Standards and Technology defines cloud computing by five features: customers can provision resources themselves, access them over the internet, share the provider’s pool of equipment, scale capacity up or down quickly, and pay only for what they use.

A bank that runs virtualised software in a rented cage has a more efficient setup, but it only becomes a cloud when self-service, automation, and metering are added.

Why this matters for Nigeria

Customers spent US$143.4 billion on cloud infrastructure in the second quarter of 2026 alone, with Amazon, Microsoft, and Google capturing about 63 per cent of that spending. None of them runs a full cloud region in Nigeria. 

Amazon has a smaller facility called a Local Zone in Lagos, but for Microsoft, Google, and Oracle, the nearest full regions are in South Africa. So when a Nigerian bank says its data is “in the cloud”, that data is often outside the country.

That is why the Central Bank of Nigeria’s order to keep payment data on local infrastructure by 1 January 2027 puts this distinction at the centre of the debate. Moving data home requires local data centres and local cloud platforms that offer the ease, scale, and reliability banks expect. Operators such as MTN, which launched cloud services alongside a new Tier III data centre in Lagos in 2025, are starting to fill that gap.
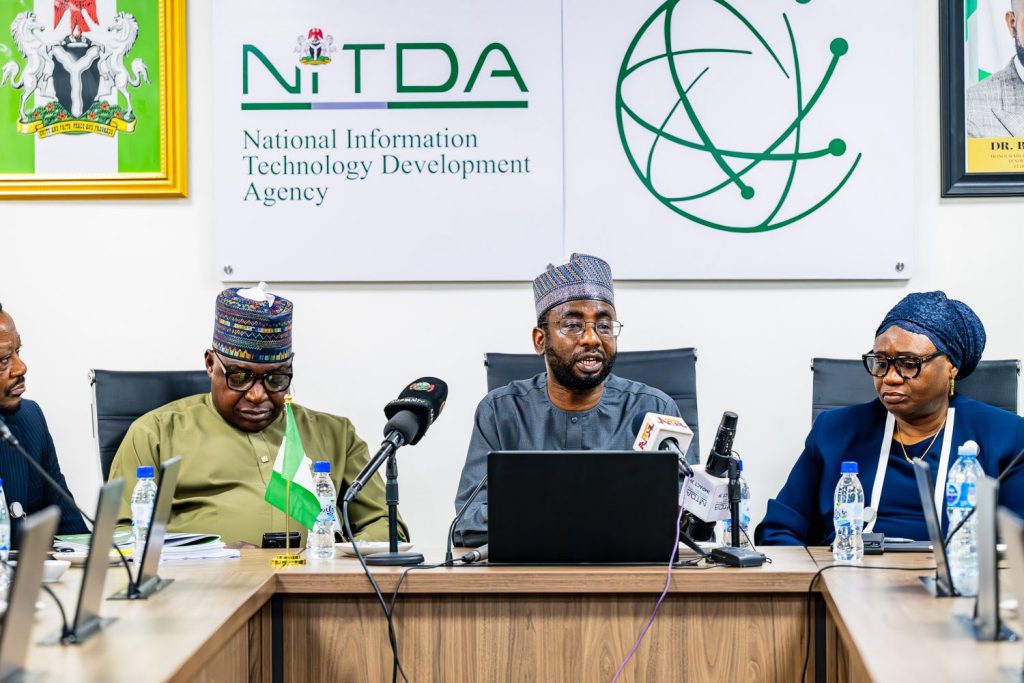
NITDA wants more local cloud operator running workloads in Nigeria
Kashifu Inuwa, DG of NITDA, during a media briefing at the National Cloud Infrastructure Summit in Abuja. Image credit: NITDA

Power and progress in Nigerian infrastructure

A Tier III data centre is built on the assumption that the public grid will fail. Rack Centre in Lagos runs entirely off-grid on its own 13.5 MW gas-powered system and reports 100 per cent uptime since 2013. Where electricity does matter is cost: generating your own power is expensive, and that shows up in prices. That is a real competitiveness issue, but a different story from “Nigerian data centres keep going down because of NEPA.”

When I chose a data centre for a bank’s workloads in 2012, there was only one commercial option worth serious consideration. Rack Centre in Ikeja opened in 2013 and later became the first facility in Nigeria and West Africa to win Uptime Institute Tier III design certification. 

Today, industry counts put Nigeria at around 26 operational data centres, about 28 including those being built, with 210 to 300 MW of capacity expected by 2030. In my experience, the leading operators have not lost a minute of service to a power failure.

A data centre is the foundation; a cloud platform is what you build on it. Nigeria now has a strong, professionally run foundation. The next challenge, made urgent by data localisation and demand for AI, is building cloud platforms on top of it. 

Policymakers, journalists, and business leaders should ask not only “Do we have enough data centres?” but “Do we have cloud platforms to make them useful?”


Remi Adejumo is a Cloud and Infrastructure Architect with over 20 years’ experience in cloud computing, data centres, virtualisation, and enterprise IT transformation across the UK, the US, and Africa.

§

On paper, it was a revolution. Over the past three years, three of Africa’s largest multi-licensed payment service providers each independently piloted a stablecoin rail. Between them, they process cross-border payments for merchants, e-commerce platforms, and remittance companies, as well as trade settlements, totalling billions of dollars annually. Their models promised to cut the cost of cross-border money movement by 10x. After stress-testing the off-ramp, each settled on a mix of stablecoin and traditional bank rails.

The blockchain worked, but the off-ramp did not. Converting back into local currency costs more than 8%, and in thin markets, the savings disappear.

Their experience exposes a truth the industry keeps skipping: stablecoins will not fix African cross-border finance until founders fix local liquidity.

I sit on a venture fund’s investment committee and back startups as an angel investor. Every cross-border fintech and payments startup that pitches me today is a stablecoin startup. Stablecoins are now table stakes for anyone building across borders. The case is not imaginary. Sub-Saharan Africa remains the most expensive region to send money to, averaging 8.5% on a $200 transfer compared with 6% globally, according to the World Bank. Chainalysis estimates that a $200 remittance sent from the region costs about 60% less when using stablecoins.

But that estimate prices the conversion off a single day’s closing rate: a snapshot of the quoted price, not the price you get at size.

Every cross-border payment does three jobs: messaging, compliance and settlement into locally spendable money. Stablecoins handle the first job well and make the second no easier. On the third, a USDC/USDT transfer is final within seconds, but finality does not equal spendability. A trader in Lagos does not pay rent in USDT. The freelancer in Nairobi cannot pay for their child’s school fees in USDC. Someone has to sell their naira or shillings, and someone has to deliver it.

The blockchain gives you finality. It does not give you naira or shillings.

The real cost sits in two places. The first is FX. Converting a dollar stablecoin into cedis or kwacha requires a counterparty who holds the local currency, wants dollars, and can trade at that moment and in that size. Outside a handful of the region’s largest markets, that pair is thin.

Thin pairs produce slippage: the gap between the price you are quoted and the price you actually get, as a large order eats through the best offers and fills at progressively worse ones. Across the CFA region, at typical transfers of $100,000, spread, slippage and payout fees together exceeded 8%.

Even vetted counterparties often lack depth, so prices are haggled over WhatsApp DMs, group chats, and phone calls between treasury desks before a trade settles. That is not a market. It is a negotiation.

Then there is someone who sits on the other side. Some liquidity pools are anonymous, and some participants are there to launder money. The leading liquidity providers deal only with businesses that have passed know-your-business (KYB) checks. That keeps the pool clean and small. The temptation is an open marketplace such as Binance P2P, with more counterparties, but many of them are PSPs whose compliance team may not be able to clear. Some providers trade with unknown entities anyway.

So the stricter your compliance, the shallower the market you can legally touch. Chainalysis reports that Sub-Saharan Africa led the world in crypto growth through June 2026, driven by peer-to-peer activity. Much of that depth is off-limits to a licensed PSP. And informal venues vanish: Binance delisted the naira from its P2P market in February 2024.

The second cost is the last mile. Local payment rails carry fixed costs and regulatory requirements that only pay off at scale. Below that scale, much of the volume is routed through cross-border rails, which the PSPs found can cost 10 times as much as a local payment. A stablecoin does not remove that cost. It moves it to the end of the journey.

The bigger mistake is the benchmark. Pitch decks measure stablecoins against the 8.5% regional average. The PSPs’ clients were not choosing the average. Globally, digital-only money transfer operators charged 3.54%, and payouts into mobile wallets cost 3.92%, the World Bank reports. Against those rails, an 8% off-ramp is priced at twice the rate.

So the PSPs now run a mix of stablecoin rails, where local liquidity is deep, and traditional bank rails, where it is not. Client costs fell from [X]% to [Y]%. It is less exciting than a revolution. It is also real.

Stablecoins still earn their place in business treasury, dollar savings and corridors with deep, licensed liquidity. But before launching one for payments, founders should price conversions at their actual ticket price on the worst day of the week, count the licensed counterparties they can use, model what happens if their main venue disappears, and benchmark against the cheapest rail their customer already has.

Where a stablecoin corridor cannot beat traditional rails, do not force it.

The next breakthrough in African payments will not come from a faster chain. It will come from whoever makes local liquidity deep, licensed and boring.


Gwera Kiwanais Partnerships Lead at Morse. She serves on the investment committee of Launch Africa Ventures and has angel-invested in more than a dozen Africa-focused startups over the past seven years. She previously worked at Monzo, 11:FS and Onafriq, and co-founded Women Who Build Africa.

Web hosting by Somee.com